

The Factory Comes With a Price Tag
As promised, this week the 🐿️ continues the quest to short list the industrials candidates for the ‘20-for-20’ portfolio.
Note for new subscribers. ‘20-for-20’ is a new Blind Squirrel Macro project that kicked off in August. The 🐿️ is seeking to step away from the short-term noise of markets and attempt to pick a portfolio of global stocks that can work under multiple macro scenarios for the coming 2 decades. Full details in linked note below:

What I did not do in Sunday’s note was review how the 2 hypothetical ‘2006 for 2026’ portfolio’s industrials picks would have performed. Let’s do that now.
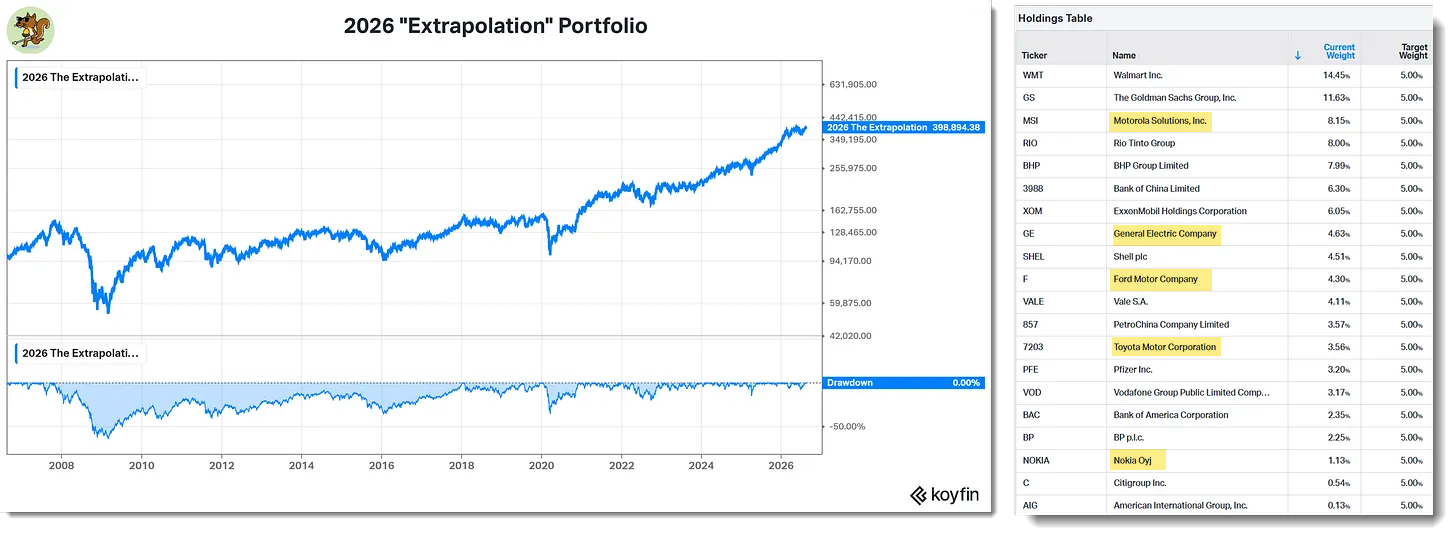
The (go with the prevailing dominant themes and narratives) ‘Extrapolation’ portfolio owned a couple of auto stocks (bad), 2 mobile handset manufacturers (very bad - if you want to qualify them as industrials) and GE (which at that time was really a financials story).
These names barely feature in today’s ‘2046’ long list. China has changed the complexion of the global auto industry in the past 5 years - a very different sector to underwrite… The 2 ‘GEs’ (Aerospace and Vernova) in the list today will need to be underwritten on a very different basis!
The (an attempt to look around the macro corners without too much hindsight 😉) ‘Mosaic’ portfolio owned 5 names (highlighted below) that all feature in today’s long list (and continue to score well as 2046 candidates).
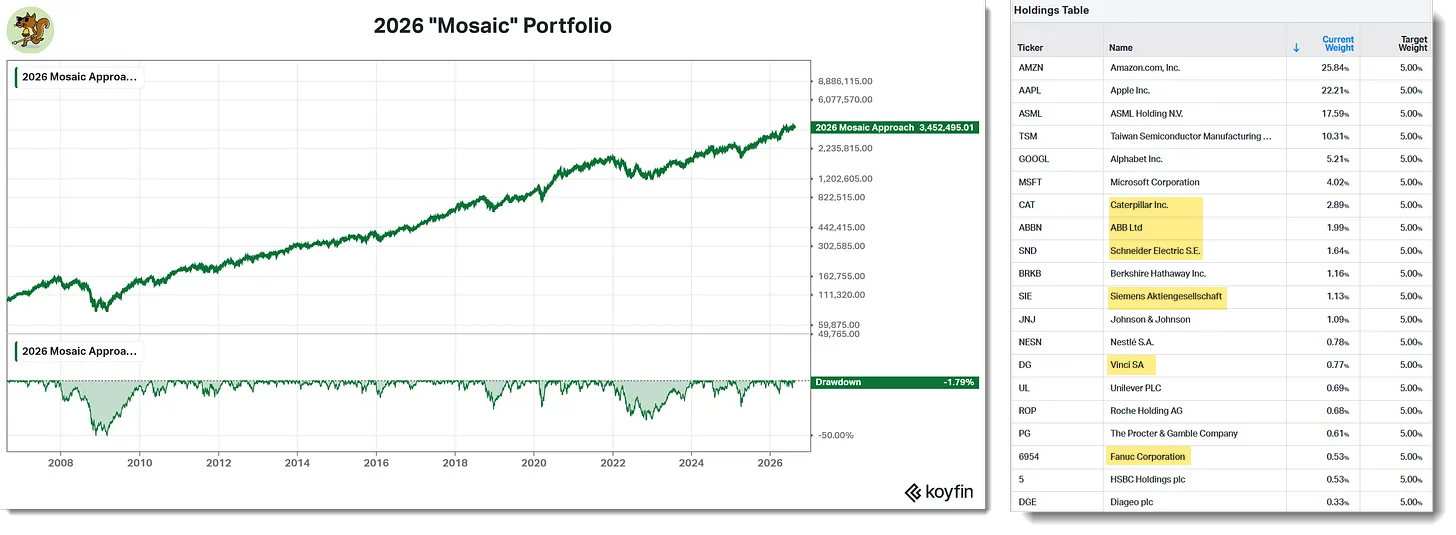
These names ‘performed’ well - all up between 4x (Fanuc) and an impressive 20x (for Caterpillar - flattered by the last 18 months masquerading as an ‘AI bottleneck bro’ stock) over that 2 decade period - but were frankly a rounding error in terms of overall portfolio attribution when set against the gargantuan moves of the big tech and chip stocks.
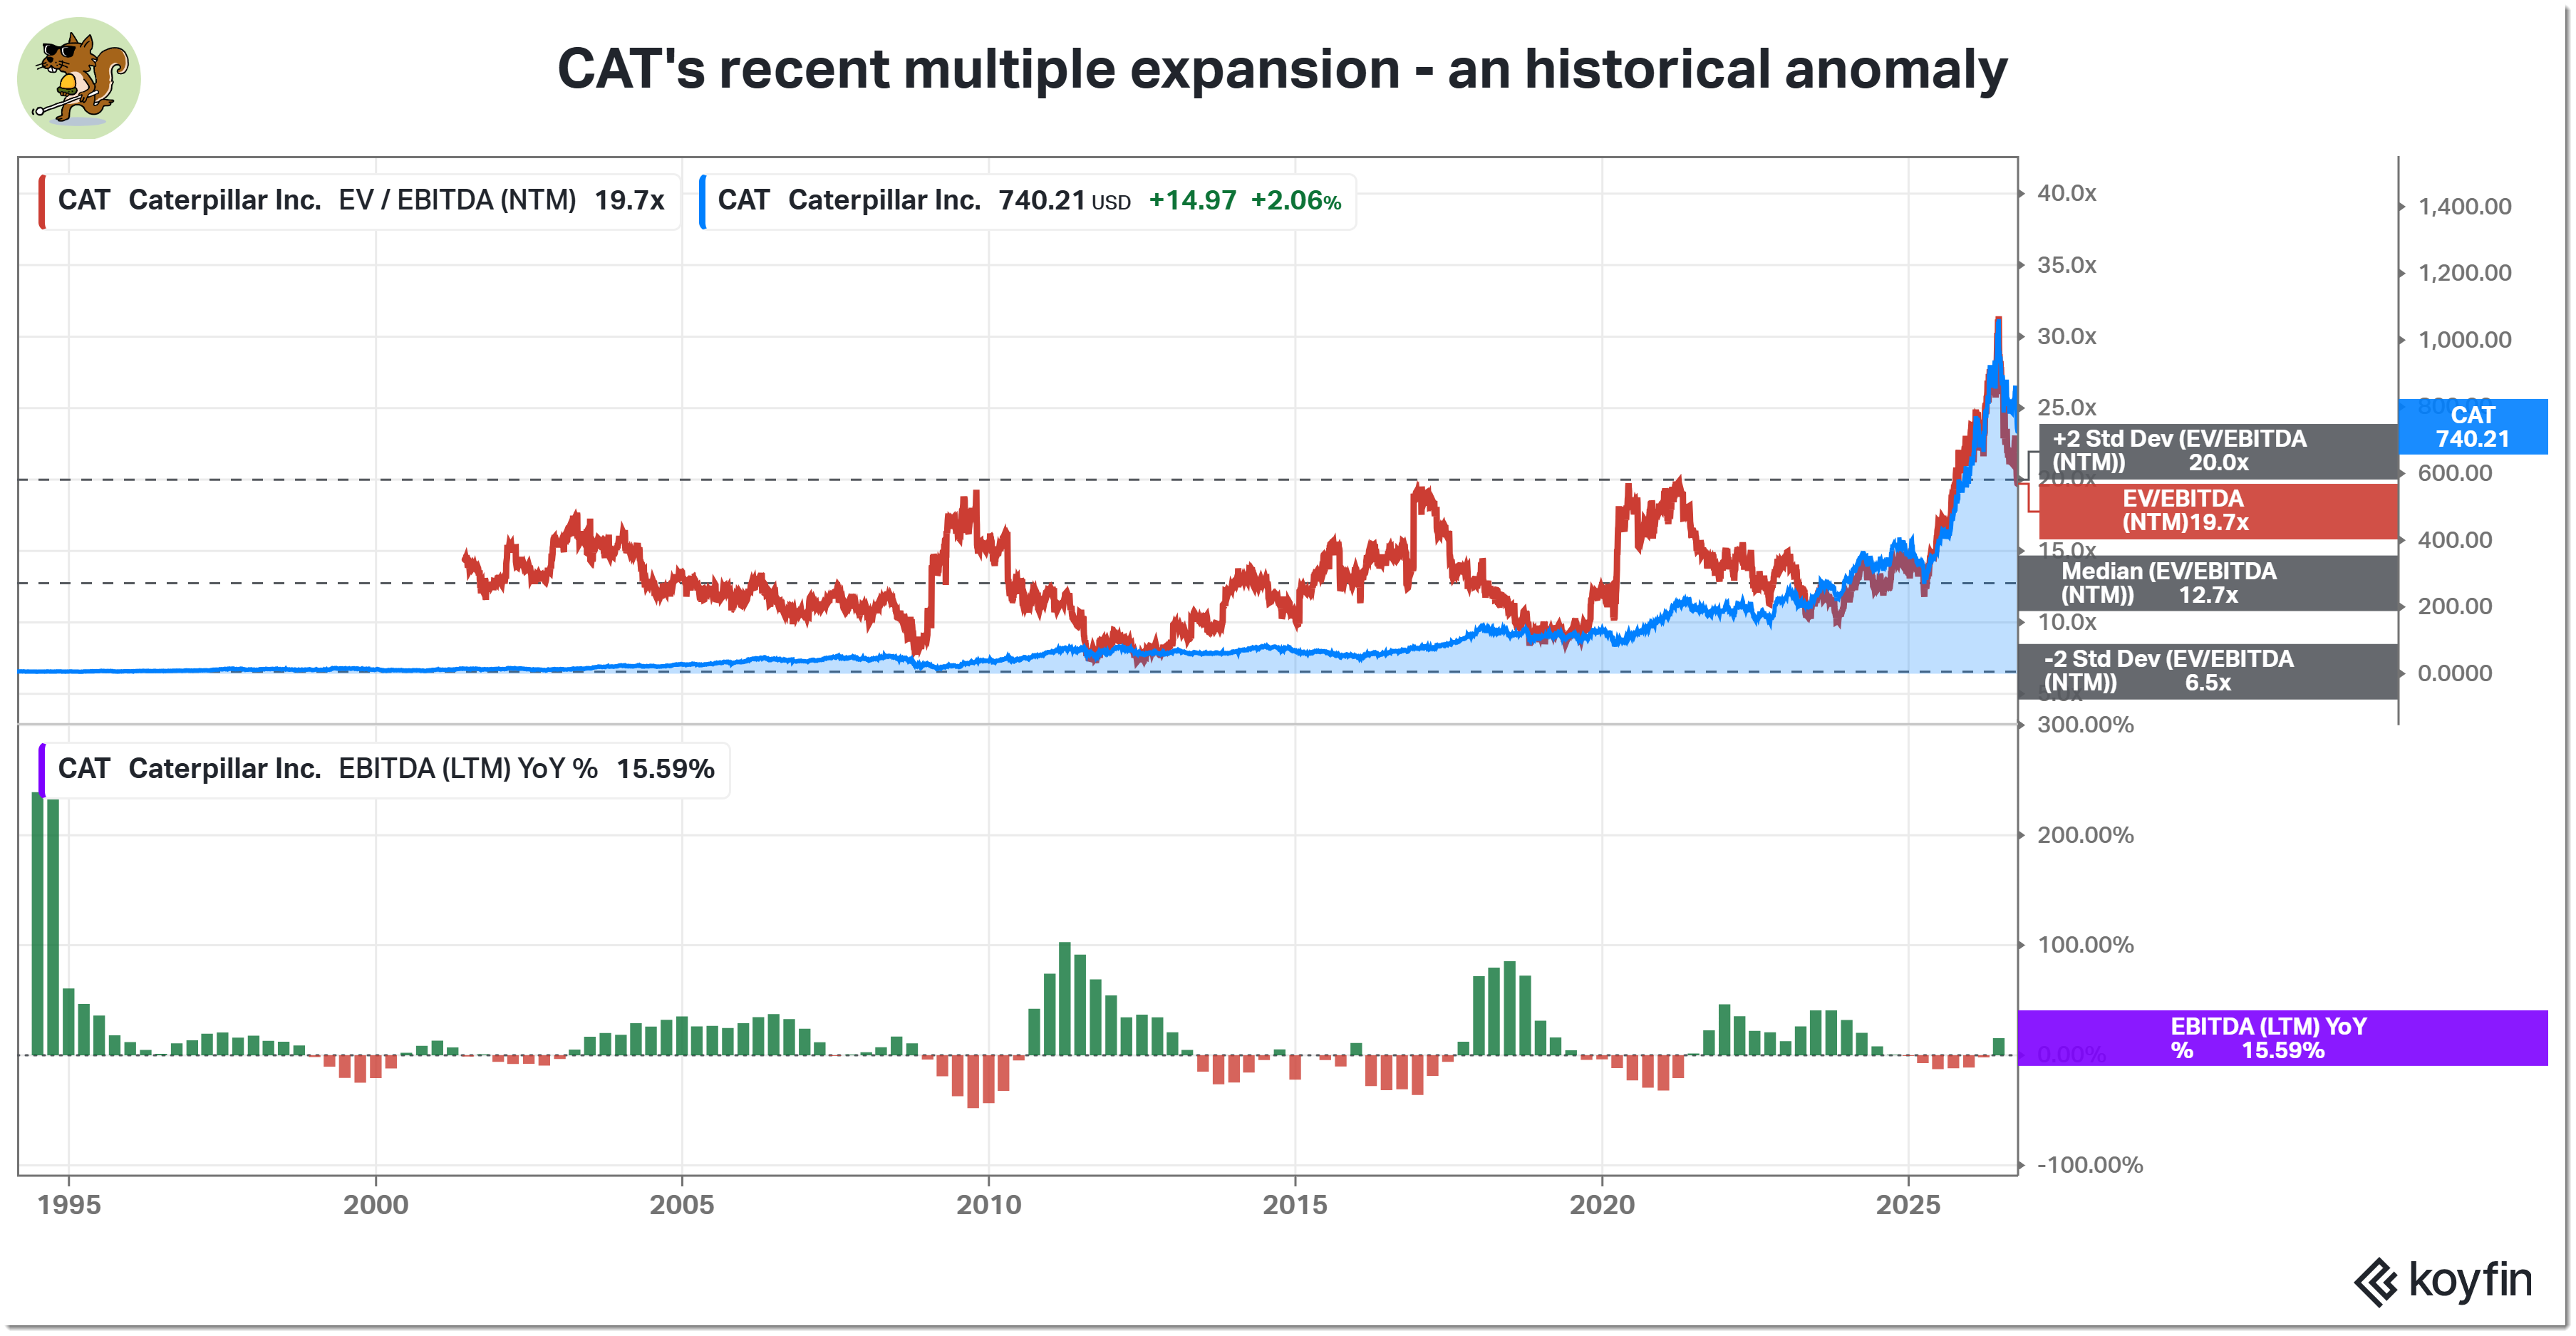
But that’s the conventional role of industrials in a diversified stock portfolio - to steadily compound returns through the cycle. The total transformation of valuation multiples and business economics for an industrial should - let’s be honest - be incredibly rare.
Underwriting the industrials sleeve of the 2046 portfolio today presents a unique challenge. Last Sunday’s note pointed out that:
Many of the industrial beneficiaries of the AI capex build, global rearmament and industrial re-shoring themes have already seen significant multiple expansion
Each of our mosaic of 10 mosaic themes has significant - in many cases binary - positive or negative first-order impacts on these sub-sectors
With much of the current narratives already well priced in to the stocks of historically highly cyclical businesses, we will have to tread carefully.
Quick Reminder of the Rules
We run each stock in the long list (full spreadsheet downloadable at the end of the note) through our 3 screens:
theme mosaic (attempting to identify winners in multiple worlds and avoid stocks that get wiped out in certain scenarios)
quality (returns on capital, free cash flow quality, moats and governance)
valuation (with a focus on implied returns and multiples relative to historical ranges)
A company can score well across the 2046 mosaic, get full marks on the quality screen and still be a poor investment at today’s price. The valuation gate is critical for the industrials group.
The 🐿️ has whittled the group down to a short list of 9 stocks from which probably a maximum of 3 or 4 (given the de-rating risks highlighted above) will make it to the final ‘20-for-20’ portfolio.
