

Blind Squirrel Macro is back to its regular publishing cadence. The weekend flagship note focused on the challenge of underwriting the industrials sleeve of the ‘20-fo-20’ portfolio. Cycle-high multiples for the cyclicals is the issue. Report here 👇:

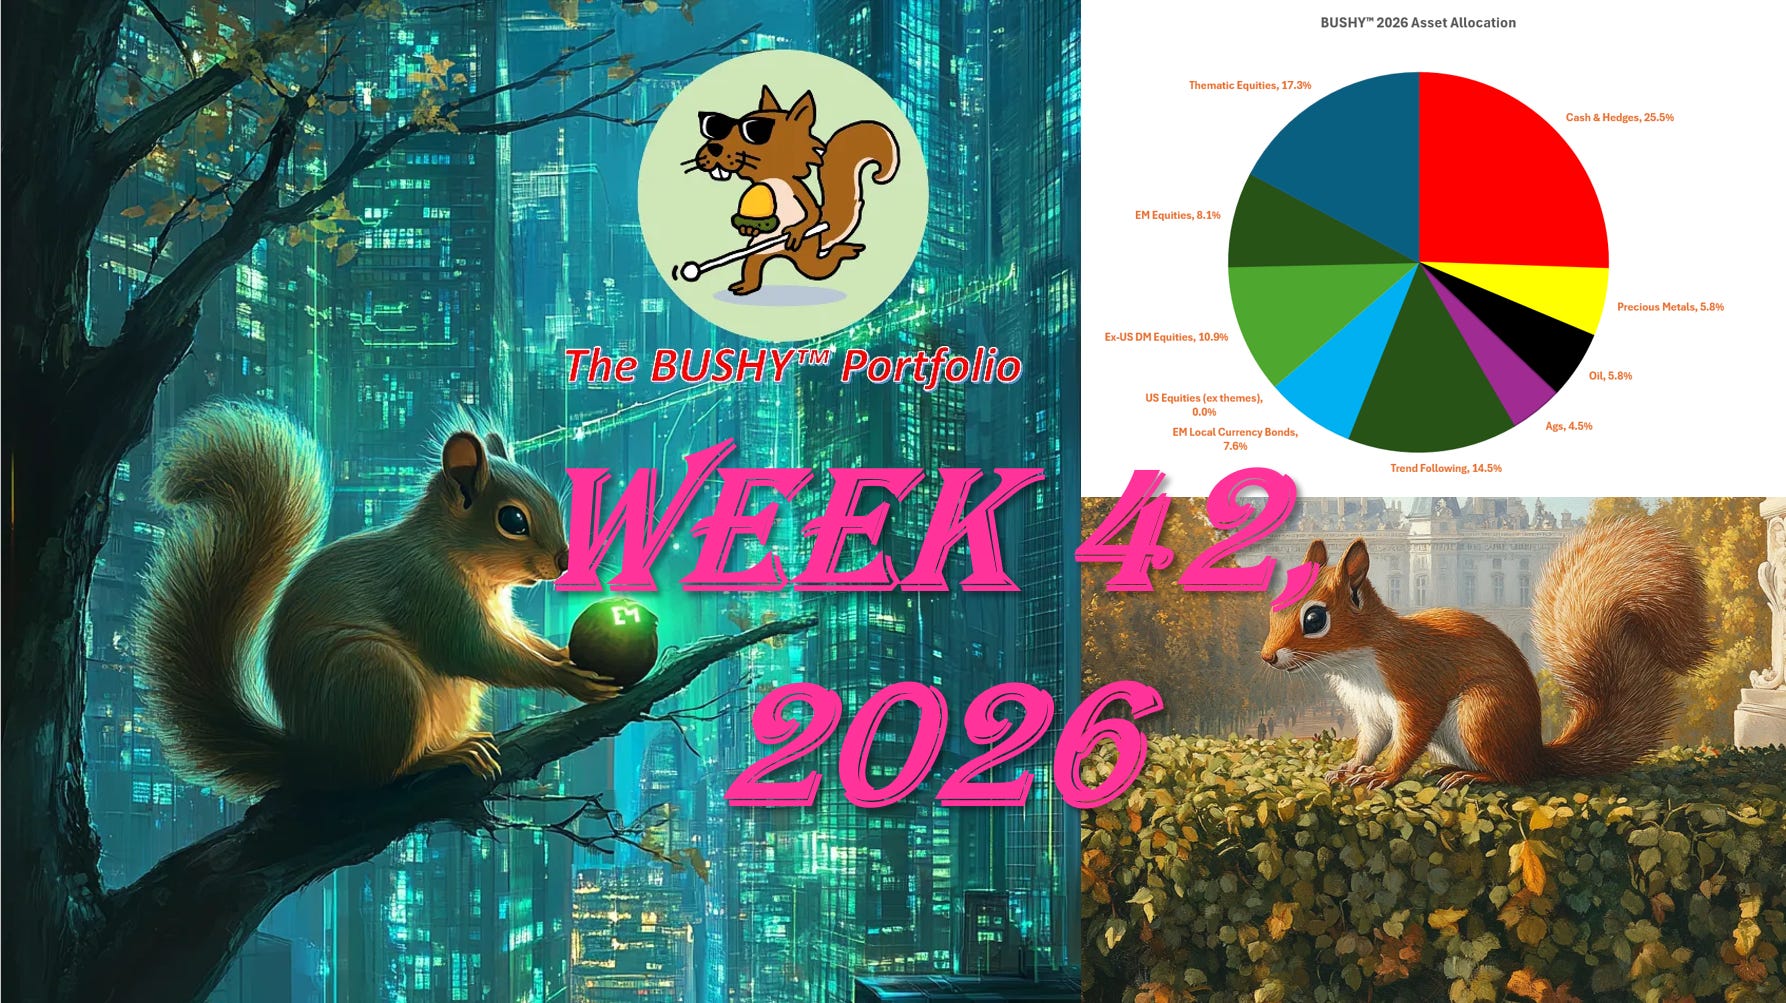
BUSHY™ held up well in the context of a tough week for global risk assets. Energy and the RSP/QQQ position in US equities provided the buffer. 2 new positions added during the week. Full report below.

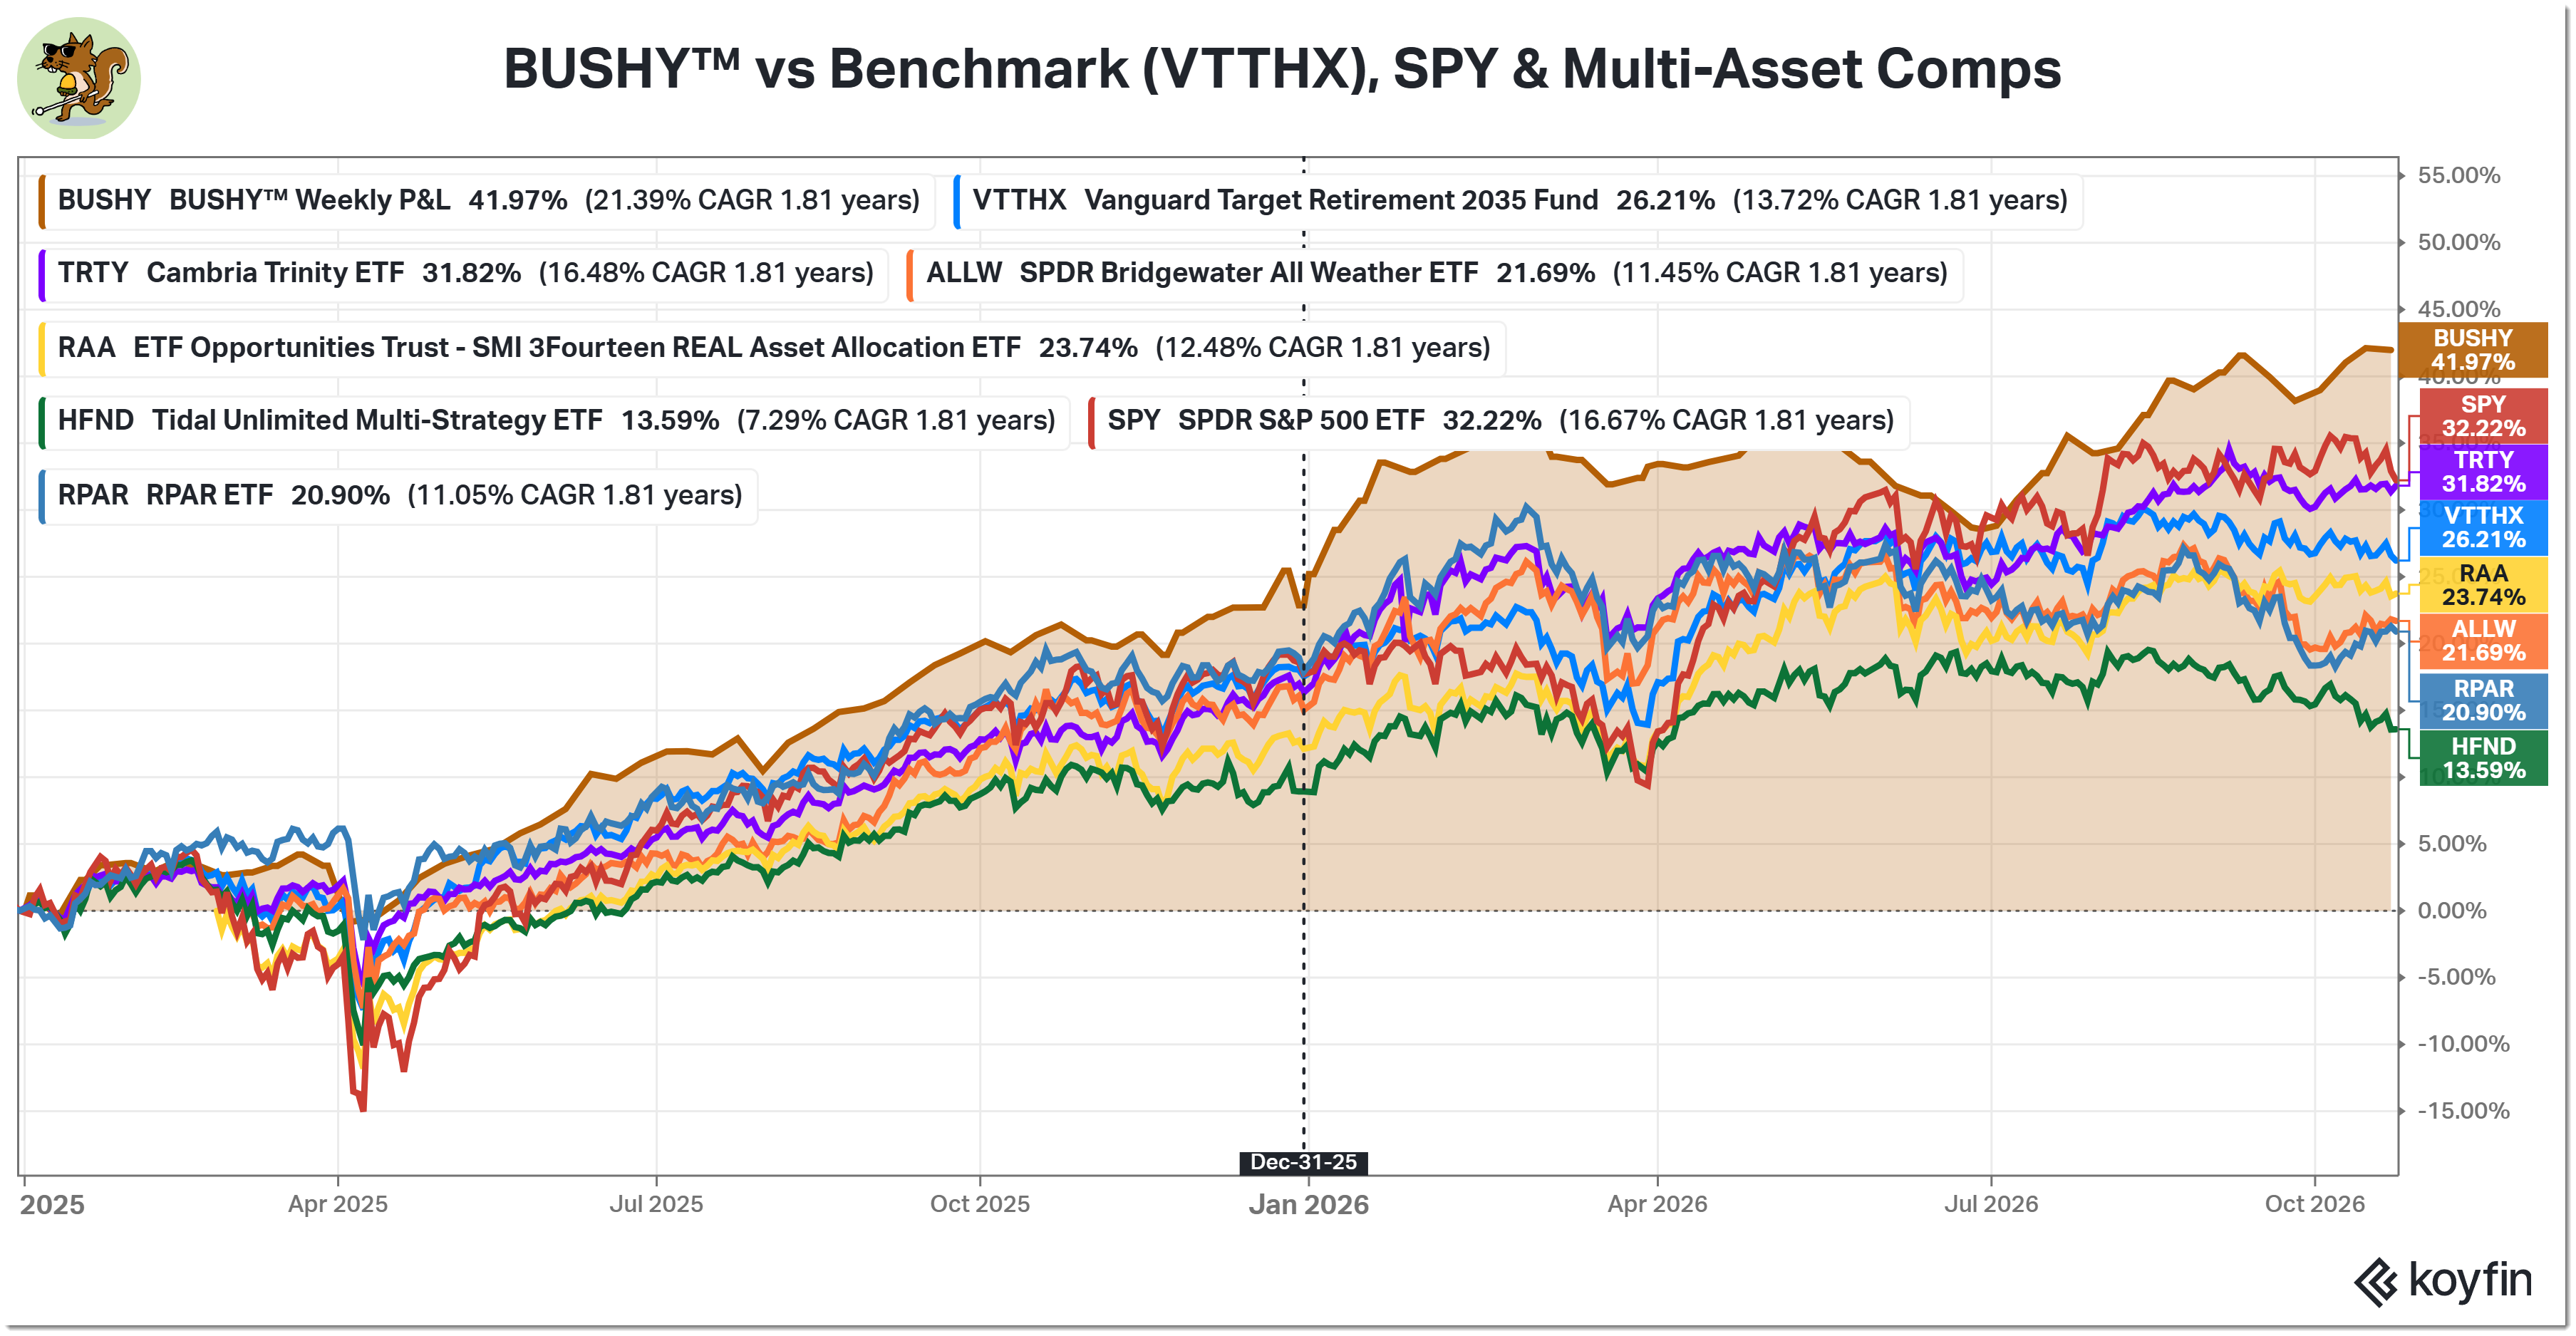
A quick reminder that the BUSHY™ portfolio is investable via a single click on the Plutus platform (as will the ‘20-for-20’ when launched) - full details in my July launch note linked below or the website via the button underneath.

Weekend Tape Bombs
Am writing this note on Monday morning (Australia time) as overnight markets absorb a number of the weekend’s market-moving events:
The shock win for Lula in Brazil’s Presidential run off. A nasty unwind of BRL and EWZ 0.00%↑ longs will be a tough start to the week for hot money pools and carry traders. Regular readers will know that the 🐿️ believes that the key driver of Brazilian equities is commodity prices, not politics. I remain a commodity bull and will be in the hunt for bargains if the sell-off gets overdone.
More anticipated news was the Conservative party’s first election win in nearly a century in British Columbia. This is another piece in the jigsaw that underwrites our overweight position in #COM (the Canadian Oil Mafia) - another win for the diversification of Canada’s energy export markets.
Anthropic’s IPO S-1 filing failed to materialize as anticipated on Friday. I cannot decide if this is a good or bad sign for the overall AI narrative. Is this a delay driven by investor feedback to the underwriting syndicate or by recent AI safety / rogue agent scares? Neither good.
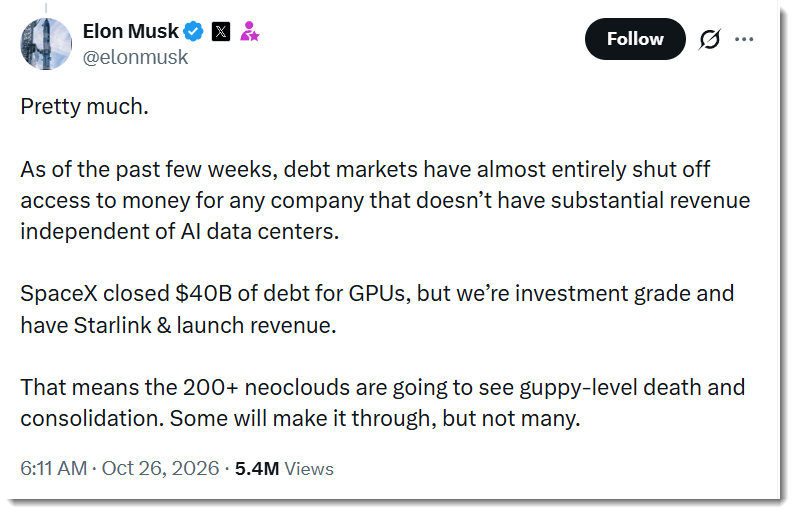
My sense is that the market is not ready to see Anthropic’s audited financial statements in their ‘full glory’. We have been teased various ARR numbers from the model labs in the past year. It is these numbers that have been the backbone of the AI capex narrative.
Concerns around this narrative have finally come for the copper stocks in the past couple of months. Our preferred play on the copper theme (plus seaborne coal and multi-polar world arbitrage) is Glencore - which has under-performed the (very pricey) pure play copper stocks and which is now flirting with its 200-day SMA for the first time since last summer.
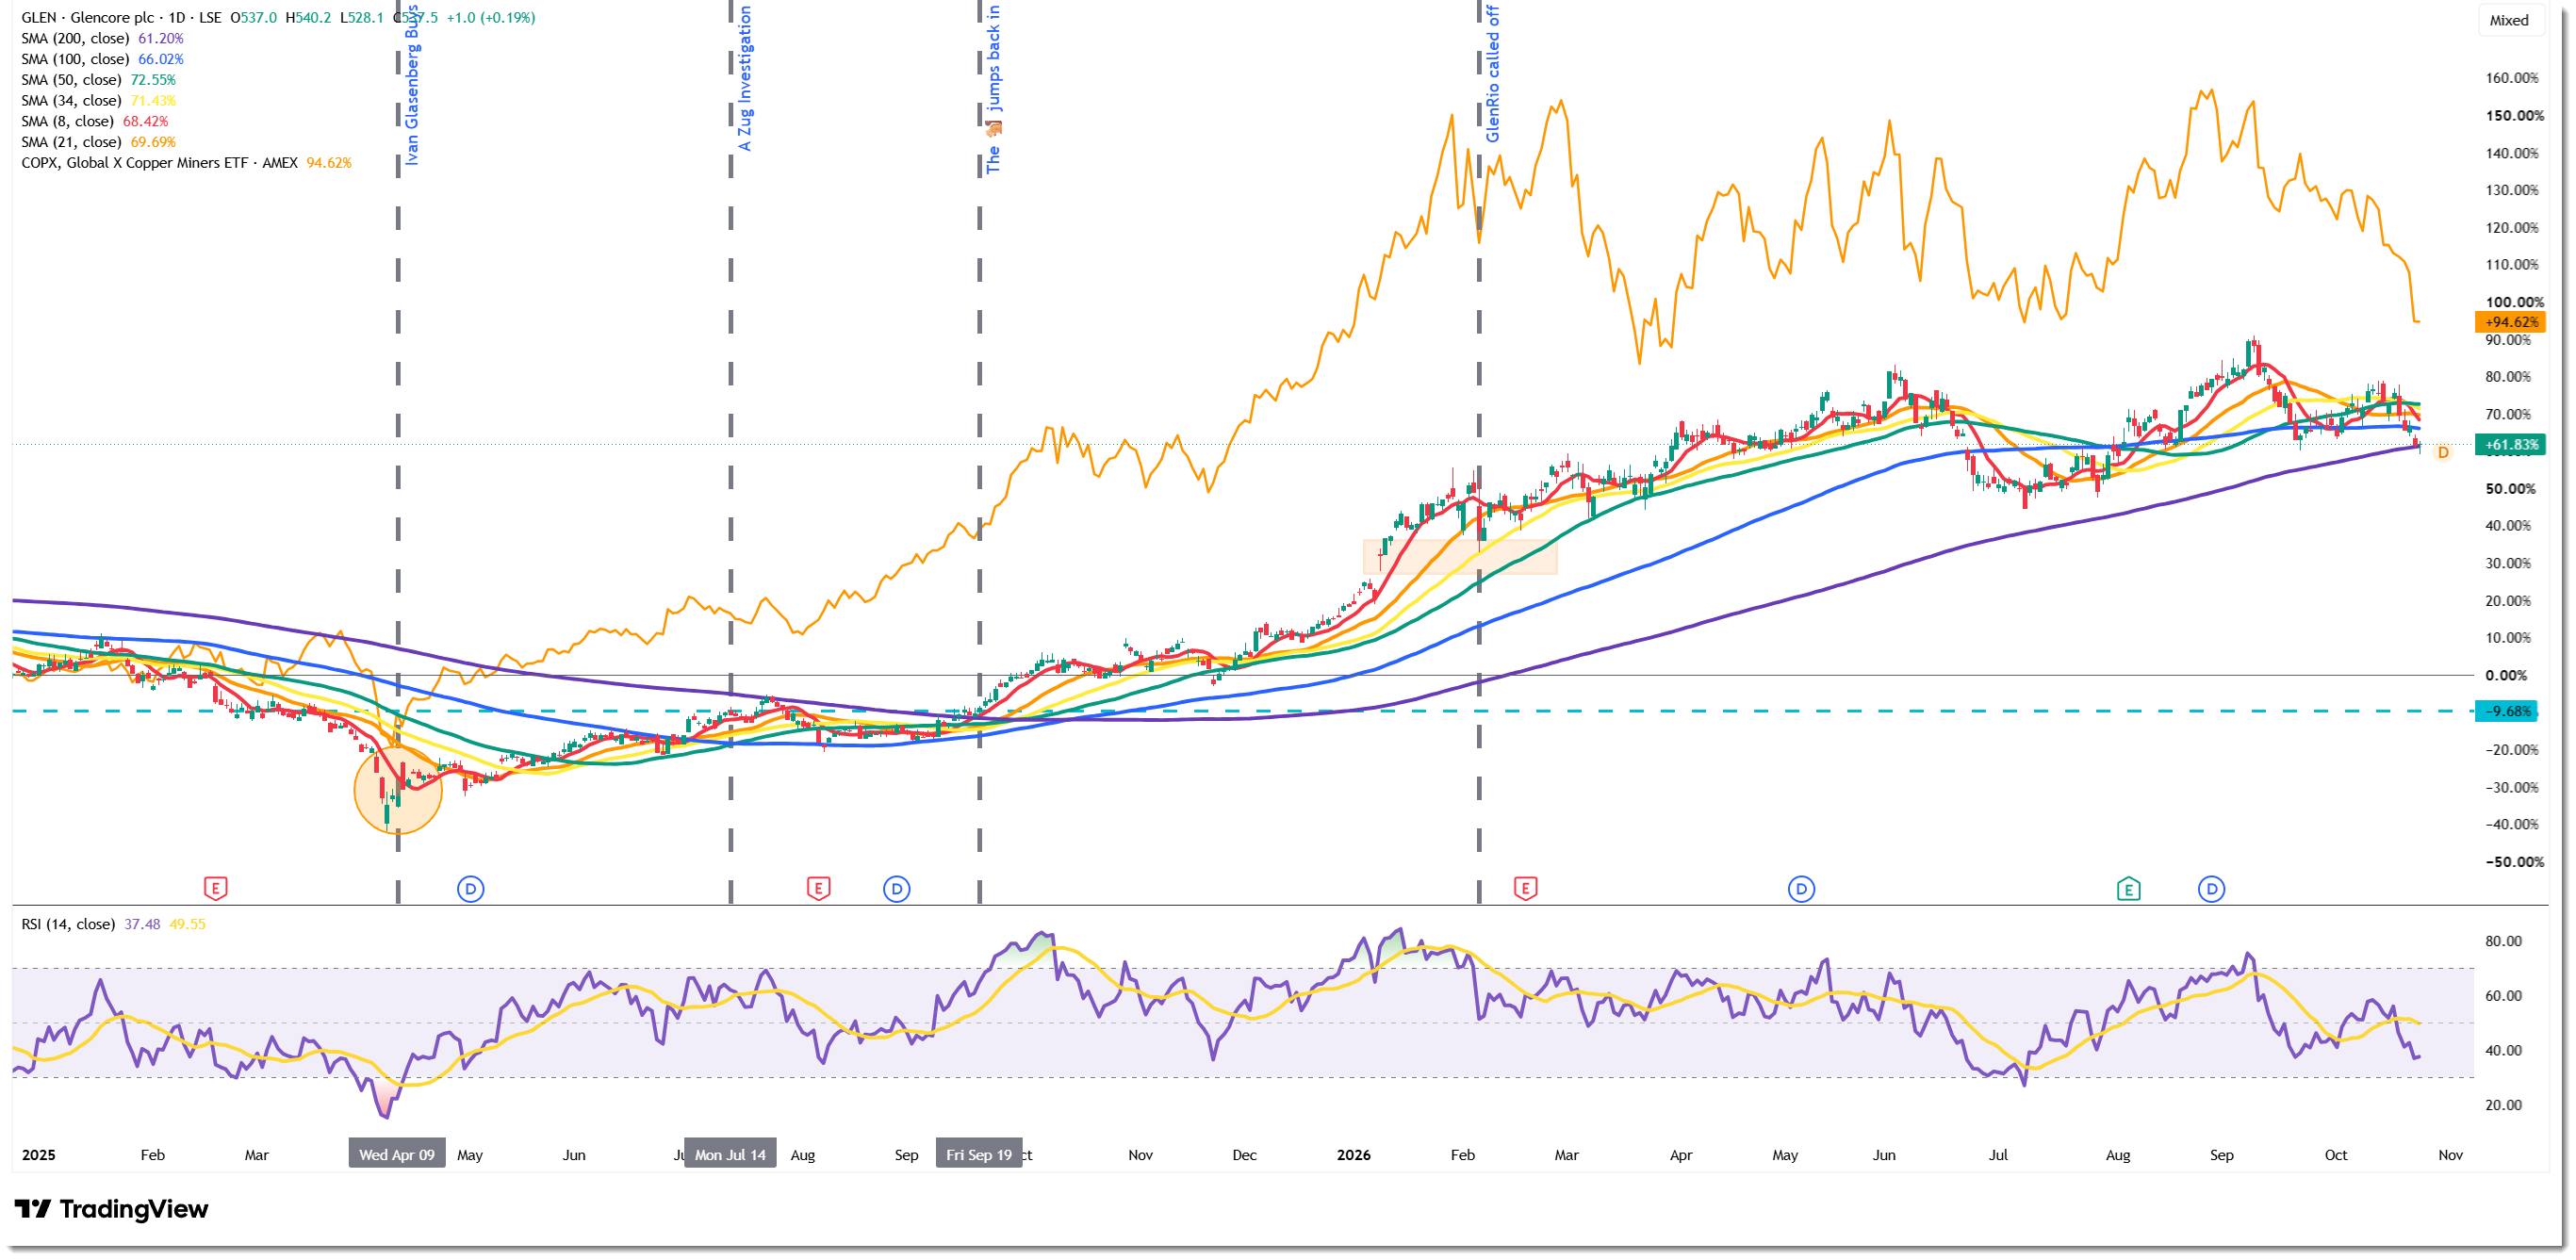
Glencore remains a core Acorn position for now. It would be naive, however, to assume that cyclical miners can be immune from a nasty drawdown if the AI-driven global growth narrative gets punctured beneath the water line.
I completely understand the arguments around ‘unlimited compute demand’ from the AI bulls. However, the more important question relating to who ultimately pays for it remains unanswered. Am not sure that Torsten Slok has a queue of colleagues joining his table at the Apollo staff canteen after this missive (‘No Signs of AI Payoff Outside the Tech Sector’) from Saturday…
On this point, Paul Kedrosky has put together an excellent AI capex revenue hurdle calculator. It translates AI capital expenditure into a required level of supporting external revenue. It then expresses that requirement relative to GDP, global software revenue and the US white-collar salary pool.
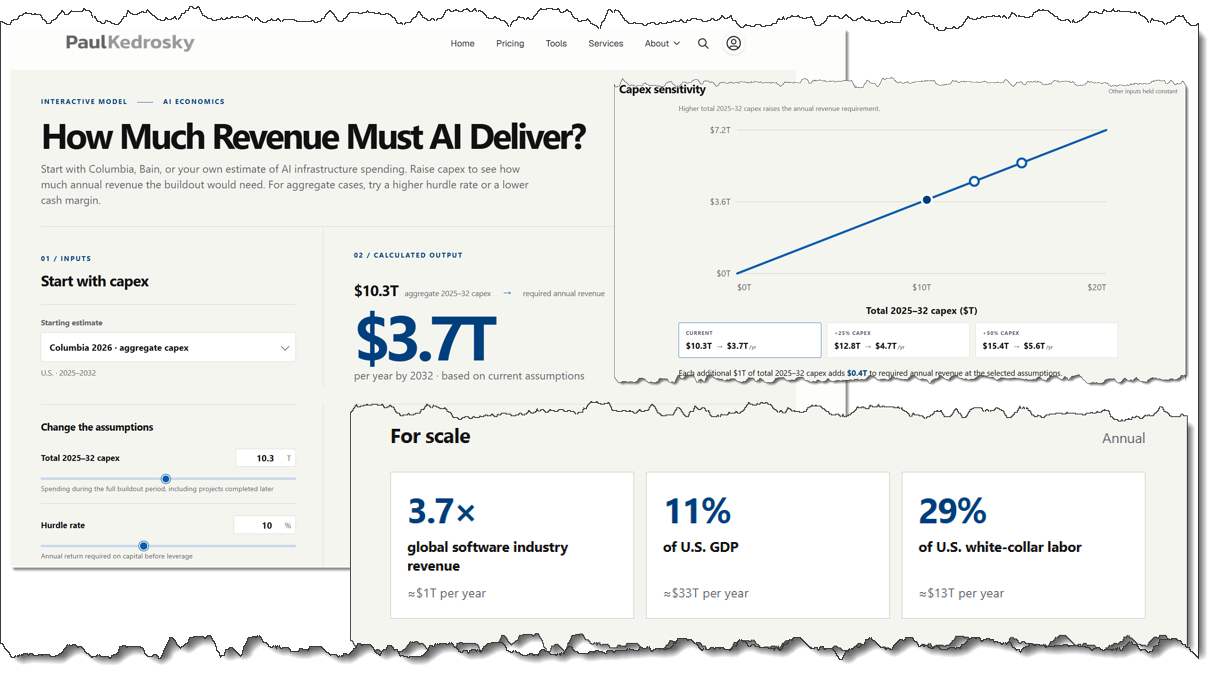
The calculator poses some tough questions.
BUSHY™ Review and Acorn Update
We added 2 new positions to the beta portfolio last week:
