

The Average of Zero and Infinity is…
There is no paywall on this note, please feel free to share far and wide. There is also a coupon for a free trial of the 🐿️’s paid service at the end of the note. We would love to have you on board!
A line doing the rounds on Palo Alto’s Sand Hill Road is “the average of zero and infinity is infinity” as they justify their increasingly large bets on AI startups.
The problem with this argument is the corollary question - how many shares of such a company should you buy? The answer is 1 share! An approach that does not fund too many data centers - well not unless everyone on the planet buys in and grabs one of those lottery tickets!
Of course, expected value analysis breaks down when one branch of the future is - at least theoretically (according to some narratives) - unbounded. An infinite right tail is obvious hyperbole - so, let’s replace infinity with a deliberately extravagant $120 trillion equity valuation (roughly one year of global GDP) - then at least have some numbers to play with.
That S-1 (finally) Dropped
So much for the 🐿️’s concerns last weekend that delay of the publication of Anthropic’s S-1 was as a result of some kind of revolt on the part of those investors given an ‘early look’ at the AI model lab’s financial statements.
On Monday it finally dropped.
Don’t worry - this note is not a tear down of the $ANT filing. If you are after one of those, I highly recommend checking out Brandon Carl’s interactive tool that allows you to interrogate the document. Brandon also joined Benny & The Squirrel on Friday to explain his excellent work in more detail.
Bulls and bears alike saw what they wanted to see from the prospectus:
The bulls pointed to staggering growth rates and ‘operating losses’ considerably more modest than the cashflow incinerator promised to us by the bears.
Bears with limited knowledge of fair value accounting for derivatives seized upon the non-cash losses created by the company’s pre-IPO convertible debt.
Those (including the 🐿️) that expected a new vocabulary of non-GAAP adjustments to restyle ongoing foundation model training as capex - the famous EBTIT (earnings before TRAINING interest and tax) - were left pleasantly surprised.
Journalists (as ever) had a field day with the over 90 pages of alarming risk factors (to be fair, some of the p(doom) was more extreme than the usual prospectus boilerplate!).
Regular readers will know that the 🐿️ had a go at valuing Anthropic (and OpenAI) back in August without the benefit of these financial statements.

Nothing from the filing screams at me that I should re-do the work. In my view, Anthropic’s filing describes the ‘cloud-only’ business model that it has employed to date - not the hybrid (cloud rental plus ‘Anthropic Direct’ (hardware / data center-heavy) model that will drive the business going forward).
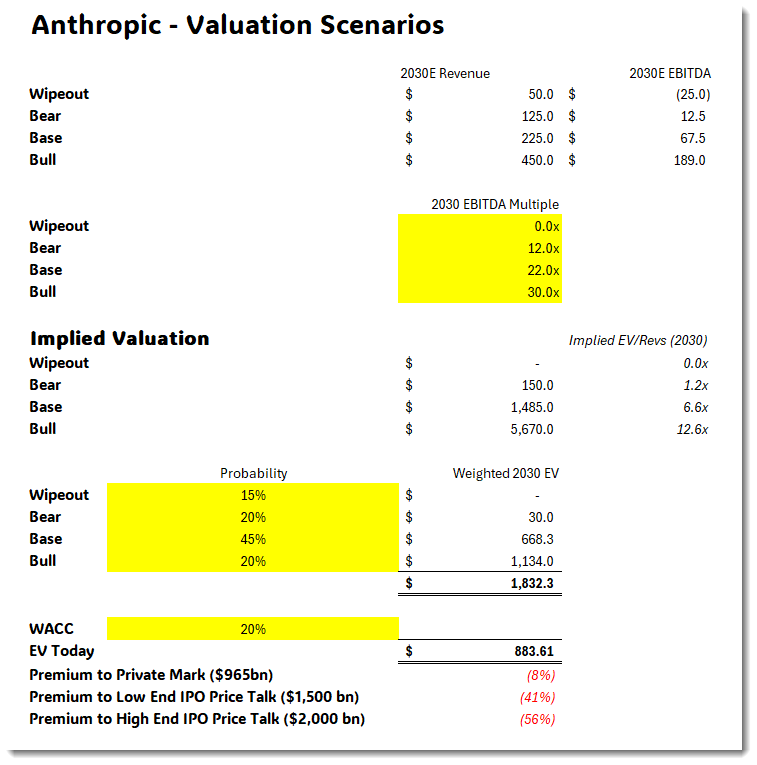
As such, discounting a series of 2030 EBITDA scenarios (described in detail in the downloadable sheet below) still makes sense. As I said back then, the 🐿️ does not subscribe to PARMAP™ (‘Pick a Revenue Multiple and Pray!’)…
A reminder of the summary conclusions (with the addition of the high and low ends of the IPO ‘price talk’):
But why should you care about some curmudgeonly rodent with a value bias and his spreadsheets? Let’s listen to the ‘man of the hour’ in his own words:
“I really do believe that we could have models that are a country of geniuses in the data center in one to two years… How many years after that do the trillions in revenue start rolling in? … If my revenue is not $1 trillion, if it’s even $800 billion, there’s no force on Earth, there’s no hedge on Earth that could stop me from going bankrupt if I buy that much compute. Even though a part of my brain wonders if it’s going to keep growing 10x, I can’t buy $1 trillion a year of compute in 2027. If I’m just off by a year in that rate of growth, or if the growth rate is 5x a year instead of 10x a year, then you go bankrupt.”
Dario Amodei in conversation with Dwarkesh Patel back in February.
In essence, assigning probabilities of zero or ‘infinity’ sort of comes down to a form of act of faith.
Enter Pascal…
“Um, okay atheists? Atheists over here please… you must be feeling a right bunch of nitwits” - Rowan Atkinson as The Devil (“just call me Toby”) giving his welcome address to new arrivals in ‘Hell’. If you have not seen, do click the link - pure comedy gold.
As you can tell, the 🐿️ is probably in the atheist camp when it comes to his belief system around ‘Digital Sky Daddy’ (my pal Chase Taylor’s choice epithet for the advent of machine super-intelligence / AGI).
The famous wager of 17th Century French philosopher and mathematician, Blaise Pascal stipulates that with a huge payoff (in his case, an eternity in Heaven) and a bounded cost (belief in God), even the smallest probability of a payout is worth the cost of a ticket.
Note: For the sake of the math - we are deliberately avoiding a major problem - that of the issue of which God?! After all, OpenAI, Google, Grok and others are all claiming to have a shot at their own deity creation. Arguably, Pascal - a devout theologian - was also fudging the fact that other deities ‘were also on offer’ in the 1650s…
Let’s say that that ‘ticket’ is priced at the low end of the Anthropic IPO price talk - $1.5 trillion. Heaven (i.e., the maximal outcome) gives you an 80:1 ‘payout’ - in other words, a 1.25% chance of that $1.5 trillion becoming $120 trillion.

For a skeptical rodent, an “I won’t buy” assertion can be viewed as a forecast that those odds are longer than 80:1 (or 60:1 if IPO pricing comes in at $2 trillion). Do I really remain comfortable with the risk of being labelled a nitwit by ‘Toby’?
Before we get too carried away, we must consider the risk of Nick Bostrom’s Pascal’s Mugging. In short, this is where naive expected value reasoning gets exploited by a ‘grand enough’ promise (that cannot be verified against evidence).
Avoiding ‘Pascal’s Mugging’
So let’s refocus on that right tail. Unlike in SpaceX’s prospectus, Anthropic has not paid a consultant that nobody had heard of attempted to estimate a Total Addressable Market (TAM) for its services. The filing points to ‘knowledge work’ (i.e., white-collar labor) representing more than $40 trillion of 2025 economic value. Let’s take this as a starting point…
Obviously, this is a wage pool, not a revenue market. Anthropic’s potential share of that pie is the opportunity. Let’s back out what various valuation outcomes look like in terms of a share of that wallet.
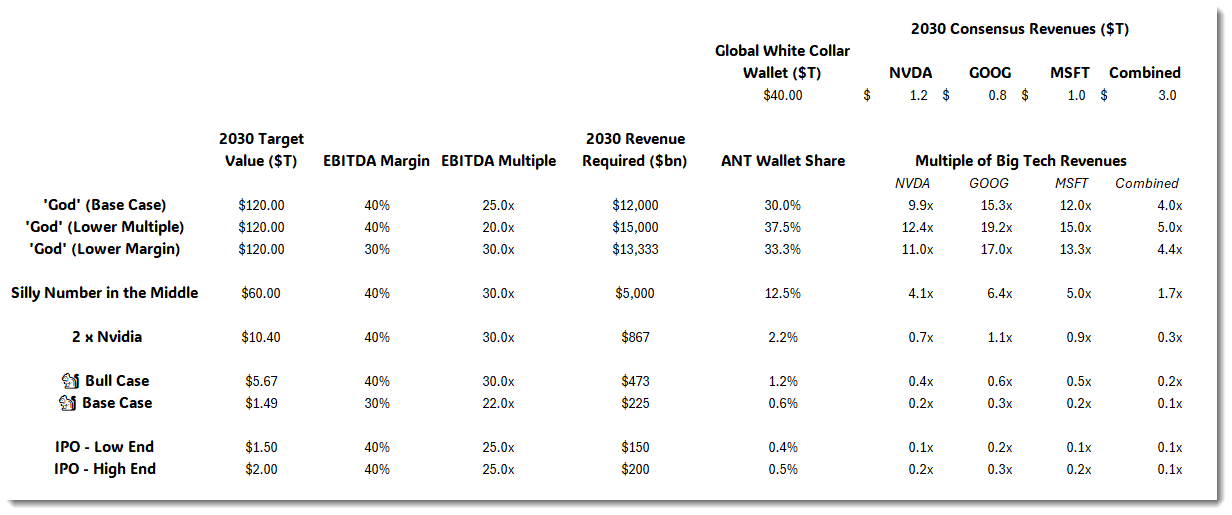
A $2 trillion IPO valuation for Anthropic implies that the company stands to capture 0.5% of that global white collar wallet. For ANT to get to a market cap equal to twice that of Nvidia today requires a 2.2% share. The digital ‘God’ scenarios require a third of that wallet to be channeled to a single company.
Suppose that a firm replaces 10 bookkeepers earning $100k with ‘Claude 10.0’, $1 million of payroll gets switched for a much smaller subscription or API fee. Multiply that across the global economy and the bull case is a wholesale transfer of income from wage earners to model owners.
I get that the bull case is not confined to replacing human labor. Abundant cheap intelligence could create demand for work that is uneconomic today (thereby expanding eth GDP pie). The techno-optimists also like to point to the fact that when Excel / Lotus1-2-3 replaced human bookkeepers, the demand for financial analysis expanded. They lean heavily on the “Lump of Labor” fallacy.
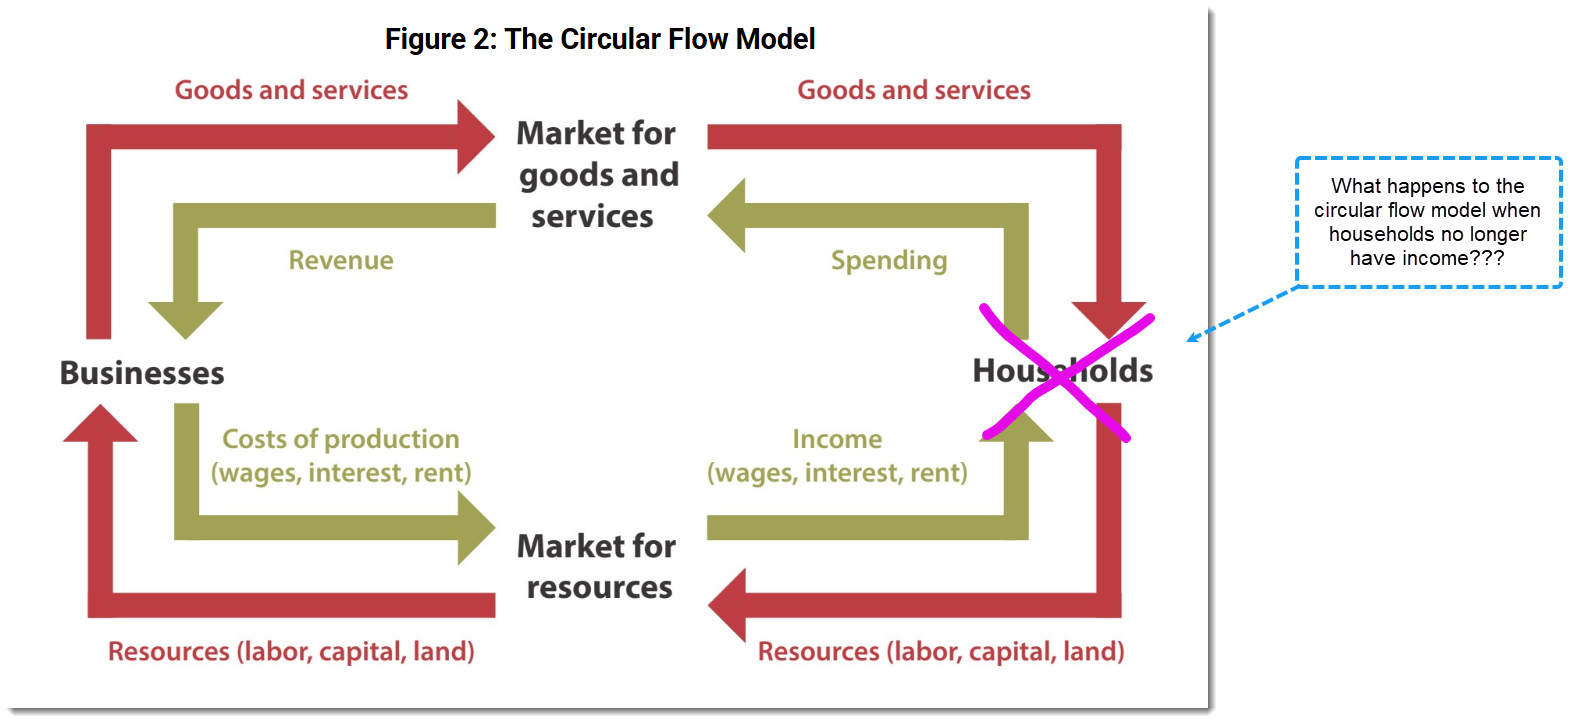
Over fifty years, new categories of work always emerge after tech disruption. However, re-skilling people and inventing new professions to cover $15 trillion of lost wages to households in less than a decade does not seem realistic.
As well as this wallet capture, all of the bull cases set out above require Anthropic to establish that market position while retaining software monopoly margins as if rival frontier labs and cheap Chinese open-source models did not exist.
None of that tells us what the $ANT stock does in its first month.
Number Go Up
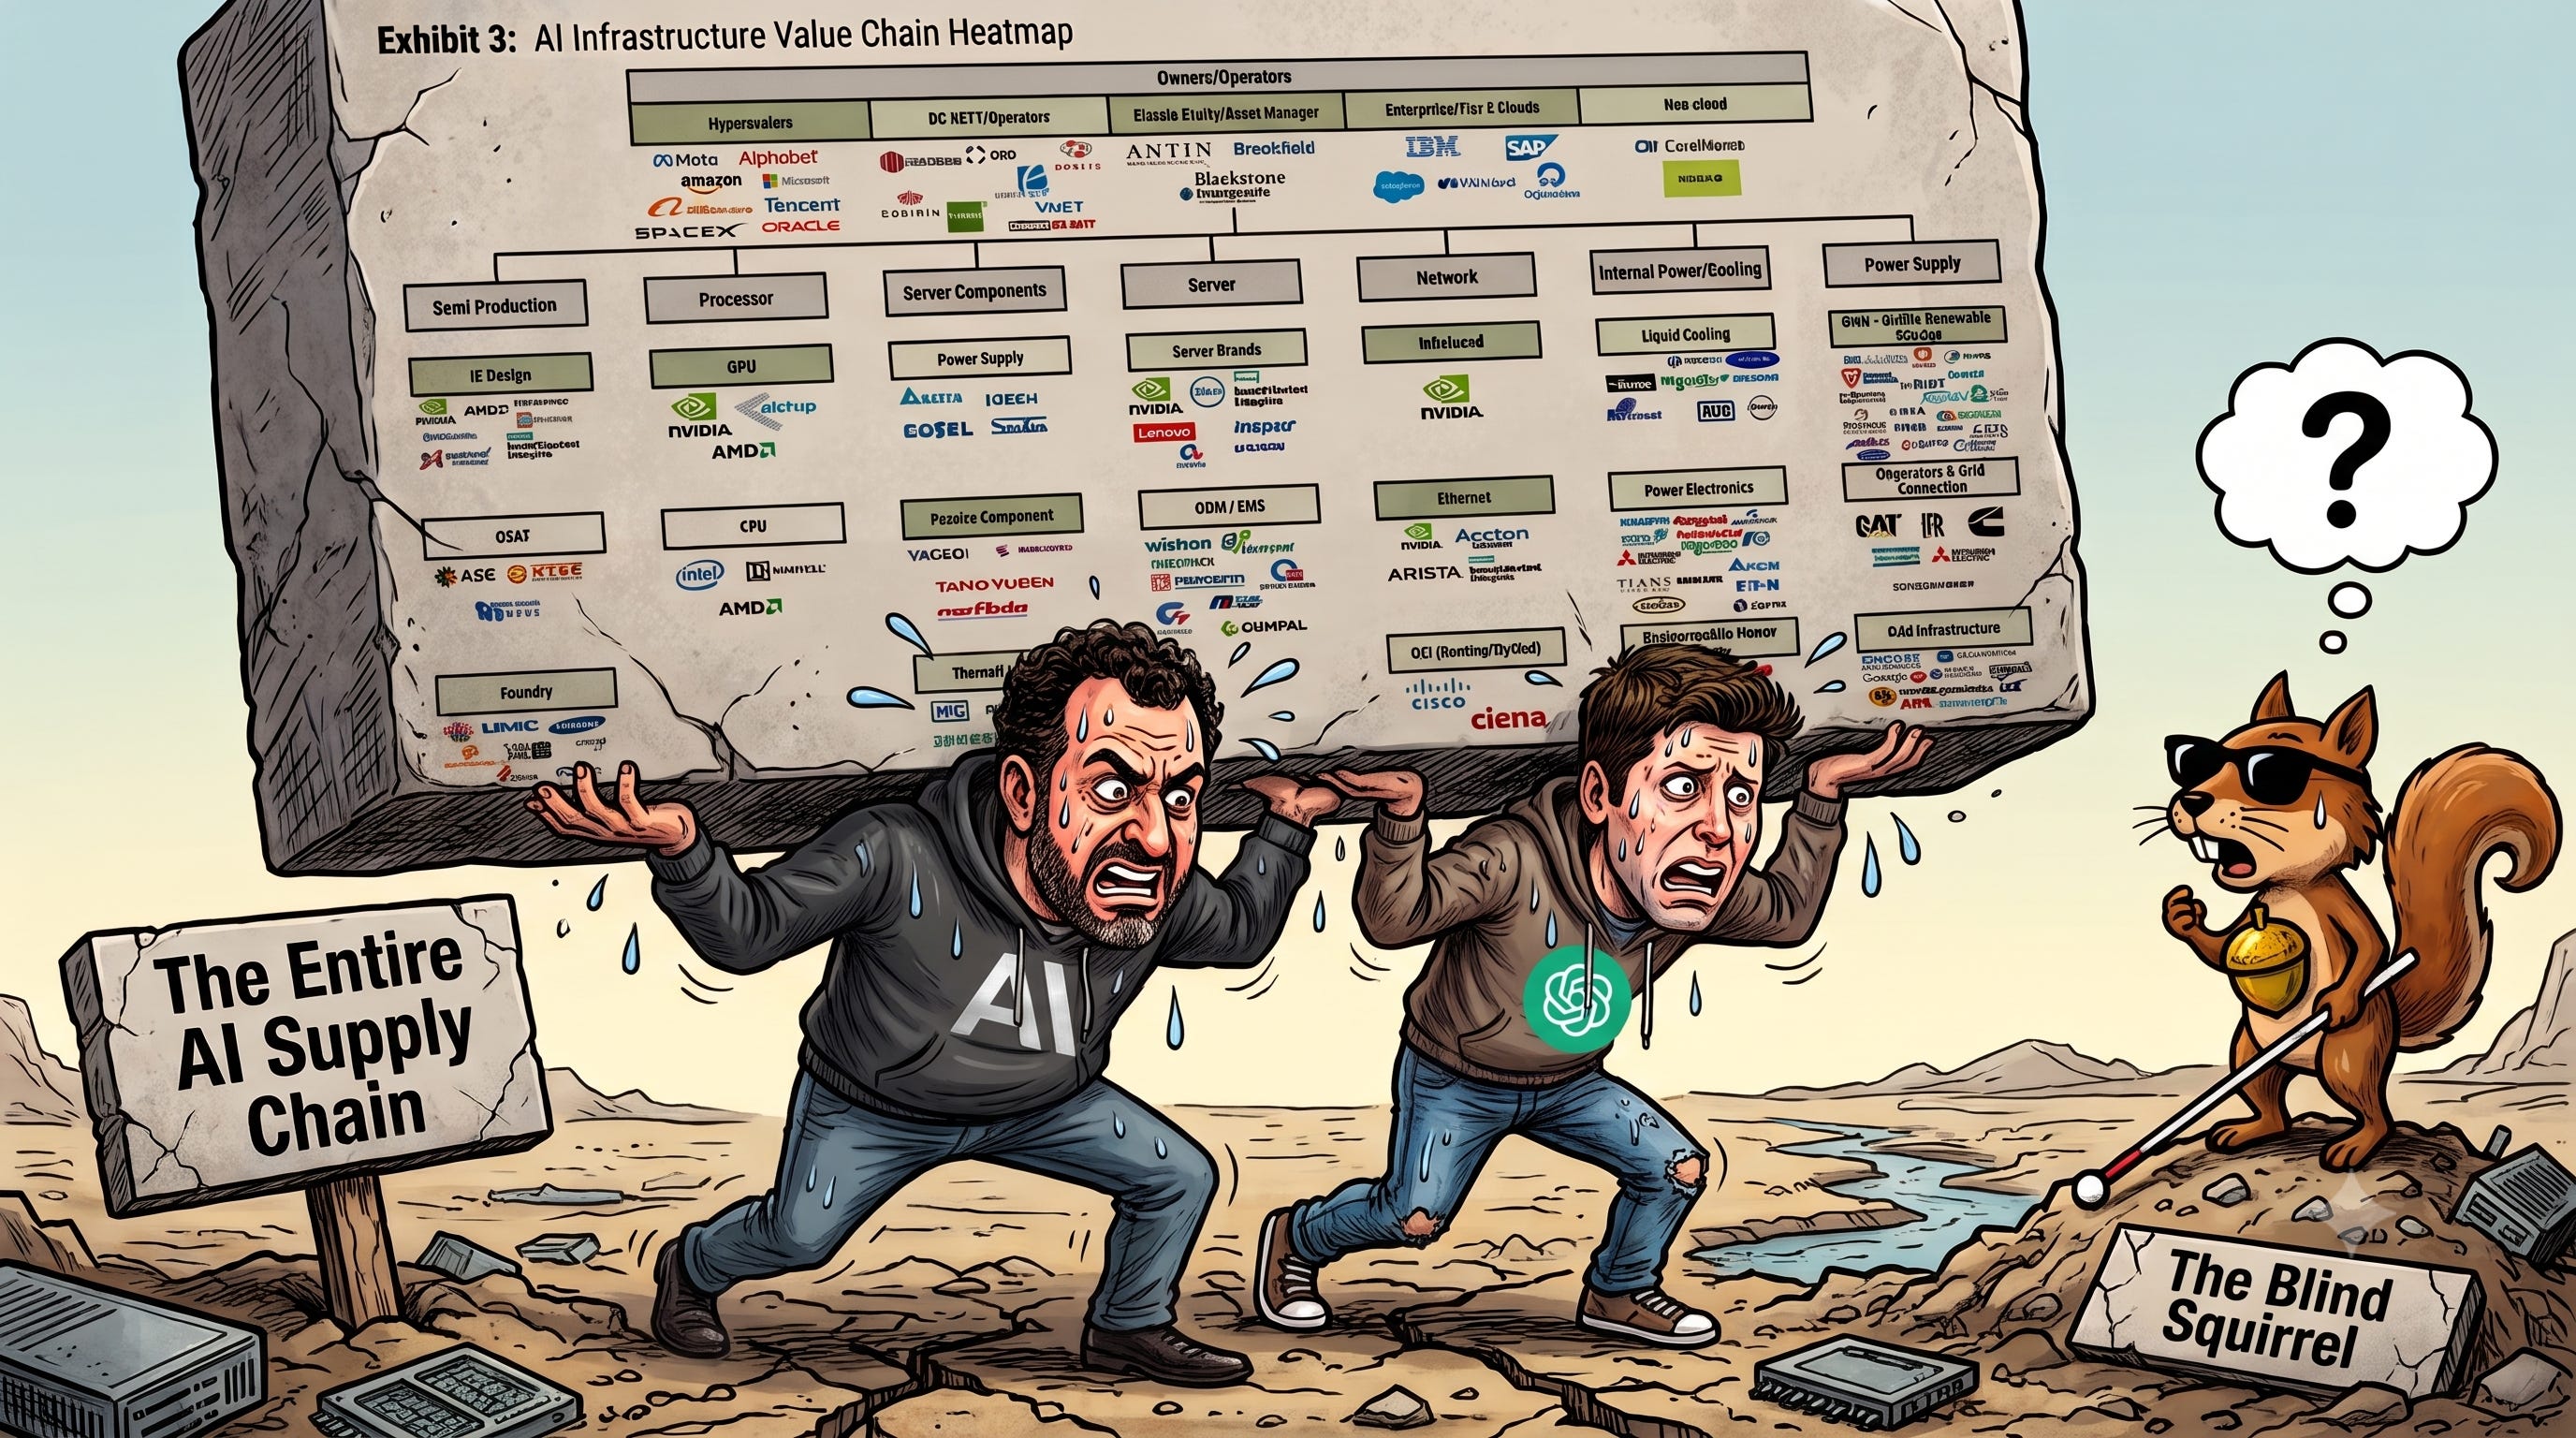
Let’s be clear. The 🐿️’s valuation work is probably irrelevant. The Anthropic IPO needs to happen and given that the foundation model labs are the cornerstones of this AI capex cycle, it almost certainly will. The wall of share supply from lock up expiries (not to mention ongoing primary supply to fund capex) will be ignored.
Raising $100 billion of fresh equity is no small feat - even for a market that has successfully absorbed jumbo cash calls from SpaceX, Google, Meta, SK Hynix etc. over the summer. But, Nvidia is already rumored to have raised its hand to take down 10% of the deal…
Retail will no doubt do its part - as they say, it is easier to sell tickets to the ghost train than to the ‘speak your weight’ machine and Dario’s rogue agents have done a great job in capturing the imagination of small investors who could have sold (but probably did not) their SPCX 0.00%↑ stock at $225 (vs $135 IPO price).
When it comes to institutions - as with SpaceX - the IPO is where FOMO and career risk kick in. Unlike SpaceX, which funded itself in private markets for decades, there is limited conventional institutional money on an Anthropic cap table that is currently dominated by the hyperscalers and Palo Alto VCs. ‘Nobody’ owns it.
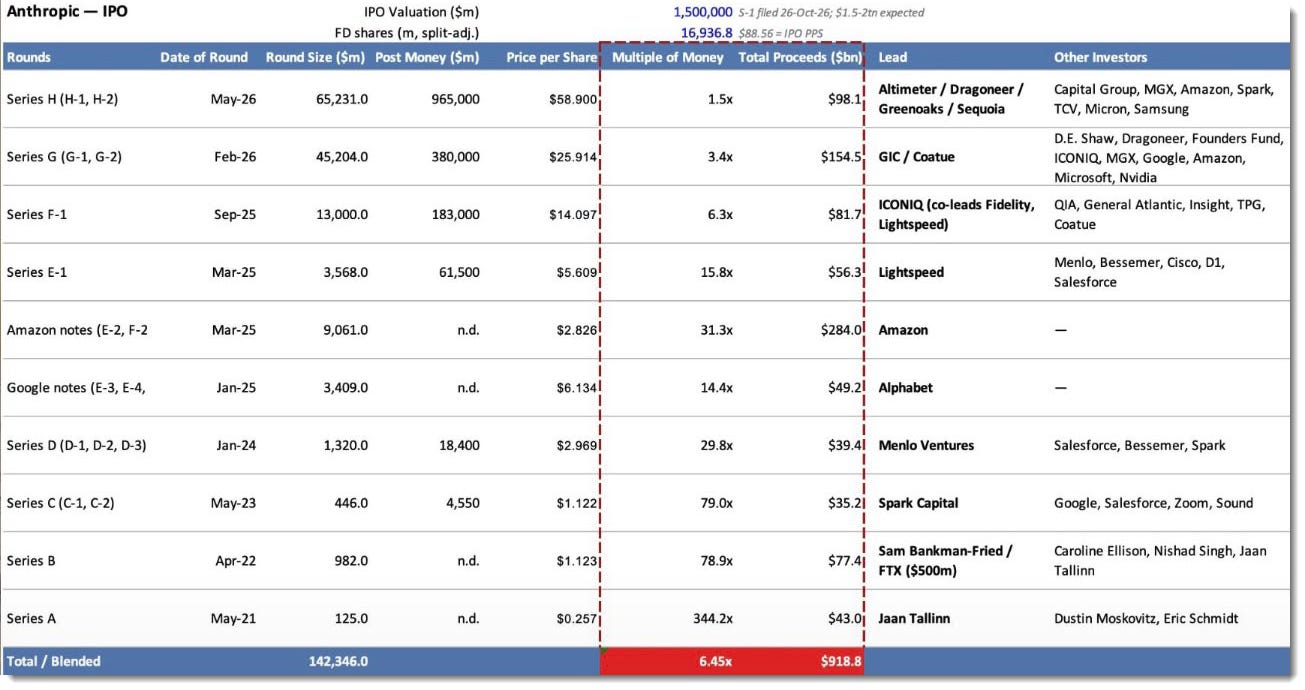
The existential threat for the professionals is not p(doom), nor is it the risk that Dario misses his 10x compute growth curve by twelve months and blows up his balance sheet in 2028. The nightmare is if $ANT lists at $2 trillion, squeezes to $4 trillion on narrative momentum and a tiny initial float during a Santa Claus rally, and benchmarked managers are sitting at a zero weight. It does not matter if $ANT is not yet in the S&P 500 or that its MSCI or Russell weighting is tiny.
In the modern asset management industry, losing 50% of your clients’ money in a ‘must own’ stock when the AI capex bubble bursts is a ‘market event’. Ironically preferable (from a career longevity perspective) to underperforming your peers because the “math didn’t math”.
The relative performance crowd will dutifully put on their 1-2% positions (doubling down on their existing AI capex overweights). Just don’t let them tell you in their quarterly letters that it’s a “disciplined ‘Fractional Kelly’ allocation to capture asymmetric right-tail convexity”. Kelly math always breaks down when fantastical payoffs are plugged into the formula.
Options
Fortunately for the 🐿️ (and most of you reading this), civilians do not have to play the relative performance game. We are under no obligation to help fund Anthropic’s 2027 data center capex bill at a chunky premium to the 🐿️ estimate of fair value.
If Dario does indeed build his “country of geniuses in a data center” without breaking the global consumer economy in the process, there are far cleaner ways to structure the bet…
We watch. A day 1 ‘pop’ could be spectacular - and it probably will ‘pop’ given the volume of cheerleading that we are seeing right now. To be honest, it may even be worth ‘stagging’ it. The 🐿️ won’t be, but have at it if that’s your thing.
If the FOMO is too strong to just spectate, there is always schmuck insurance. I expect $ANT to have a liquid listed option chain within days of going public. As a comp, SpaceX (also trying to build its own ‘Digital Sky Daddy’) currently has call open interest of c.2.5m contracts ($37bn of notional exposure at spot) on its chain.
SPCX 0.00%↑ has expiries listed out to January 2029, where the highest strike is $295 per share (more than a 100% premium above spot, 33% delta). There is $236m of spot notional camping out in that contract (OptionStrat worksheet linked to payoff table below).

A broadly equivalent structure for Anthropic should be available by Christmas.
I am constantly being told by the AI bulls that my skepticism around the value of the labs is the inability of my simple rodent brain to process exponential growth curves.
Allocating a few basis points of NAV to this type of strategy in order to have the extreme right tail covered feels like a practical way to think about an insurance policy when it comes to this deal. Not quite the bounded cost that Blaise Pascal had in mind, but equally effective.
Dear Free Subscriber. You made it to the end of the note! If you enjoyed it please take a free trial of the 🐿️’s paid service or share the opportunity with a friend or colleague.
Do get in touch if you have any questions. Also grateful for any feedback - specifically any glaring omissions!!
Until next time, Squirrel Out!
If you act on anything provided in this newsletter, you agree to the terms in this disclaimer. Everything in this newsletter is for educational and entertainment purposes only and NOT investment advice. Nothing in this newsletter is an offer to sell or to buy any security. The author is not responsible for any financial loss you may incur by acting on any information provided in this newsletter. Before making any investment decisions, talk to a financial advisor.