

Confucian Confusion
All it took was 7 candles! A 12% outperformance of Chinese stocks over the S&P 500 since the start of the month appears to have folk eyeing the Middle Kingdom as the next beneficiary of the Great Rotation Trade. Even some of the hard core China bears in pundit world…
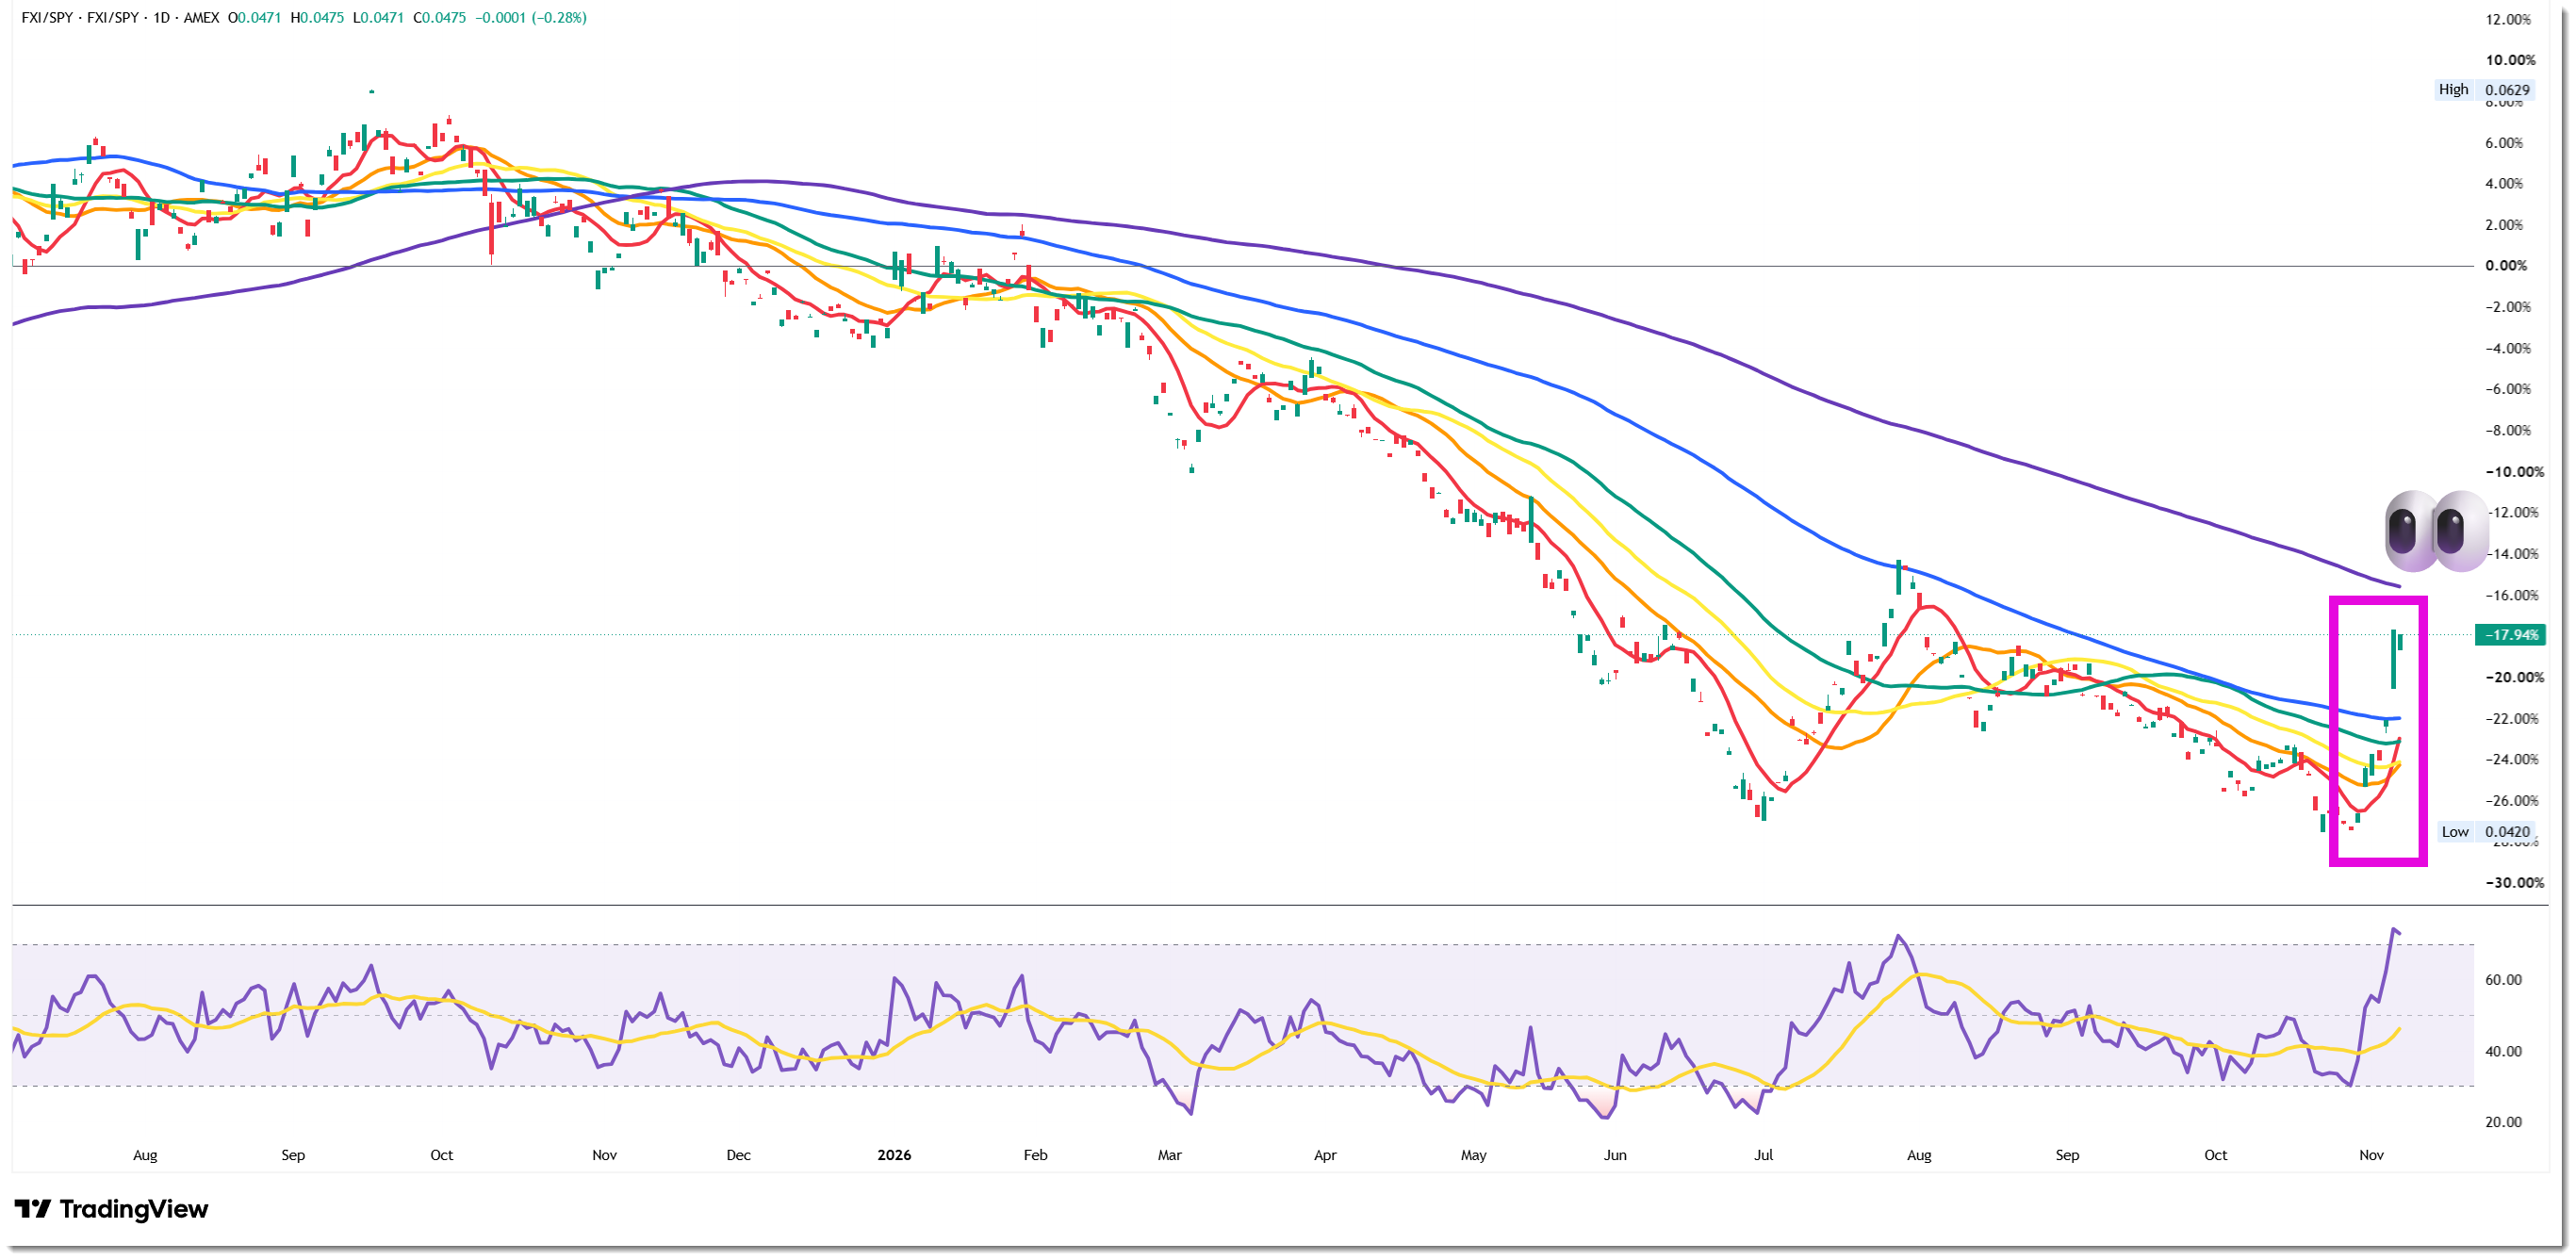
Who can blame them? When these ratios move, they really move… Who can forget the famous 4 week bull market in Chinese stocks in October 2024 (which mostly took place while China was closed for the Golden Week holiday…go figure…)?
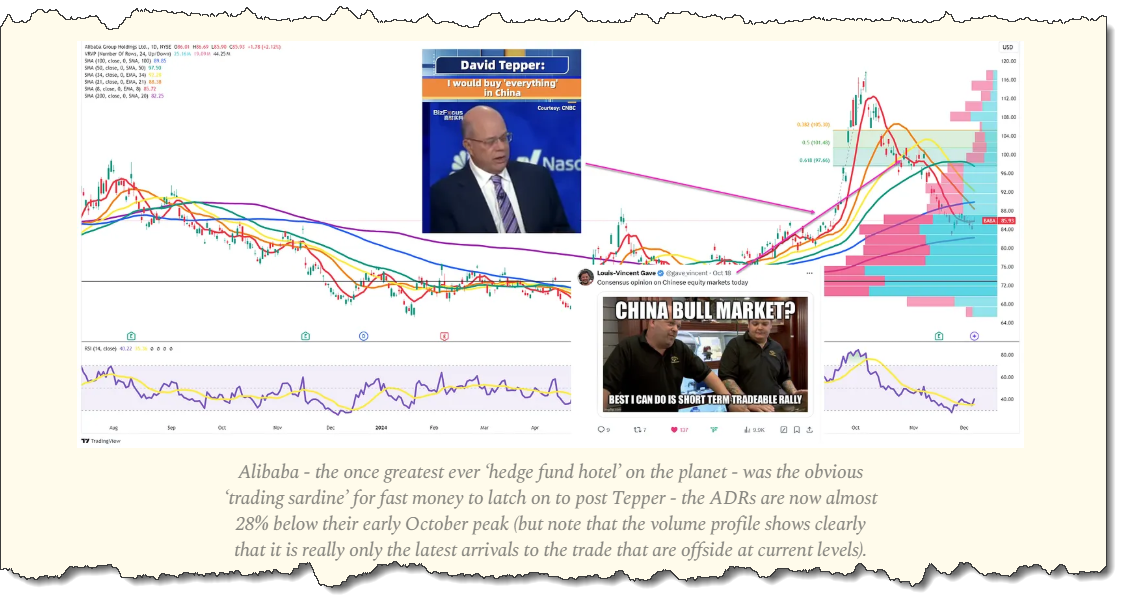
The 🐿️ has had a constructive outlook for Chinese equities since early 2024 and started to increase my weightings more aggressively during that summer.

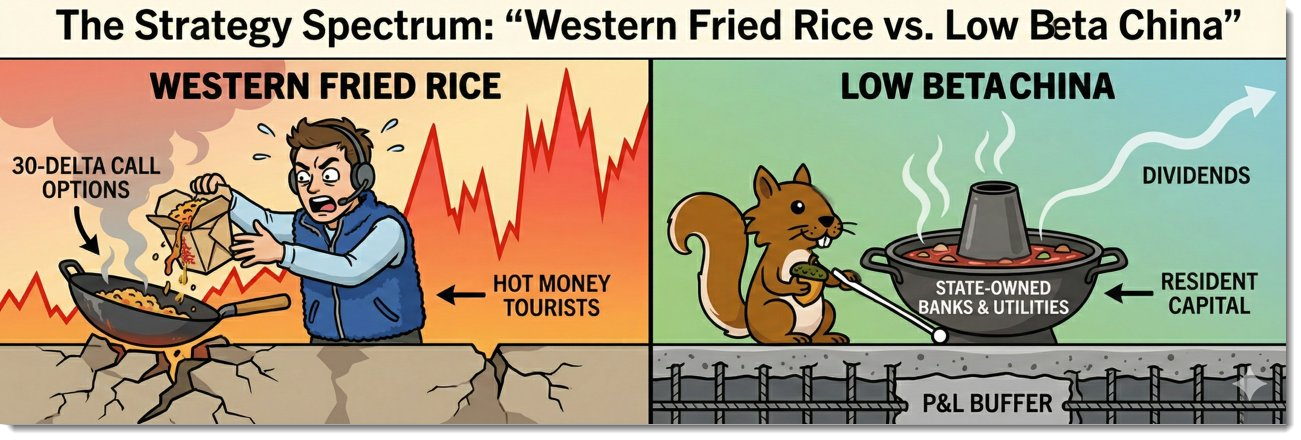
The China book managed the post-Tepper-spike drawdown well by avoiding the usual suspect ‘hot money’ stocks (aka WFR - Western Fried Rice) to focus on LBC (Lower Beta China) and ended up having a pretty solid 2025.
However, getting Chinese equities right in 2026 has been a bit of a struggle. Understatement. In fact, the irony is that the positions that have saved my China book so far this year have come from a conglomerate that owns an airline (albeit an excellent one, Cathay Pacific) and from picks within a sector (healthcare) in which I have had a patchy (being generous!) track record over the years!
I came into the new year believing that the worst of the US / China trade war was in the rearview mirror and started to add to my broad-based exposure to Chinese equities (‘Knowing your ABC’). Instead we got a hot war in the Middle East, triggering a significant cut back in EM & DM equity risk.
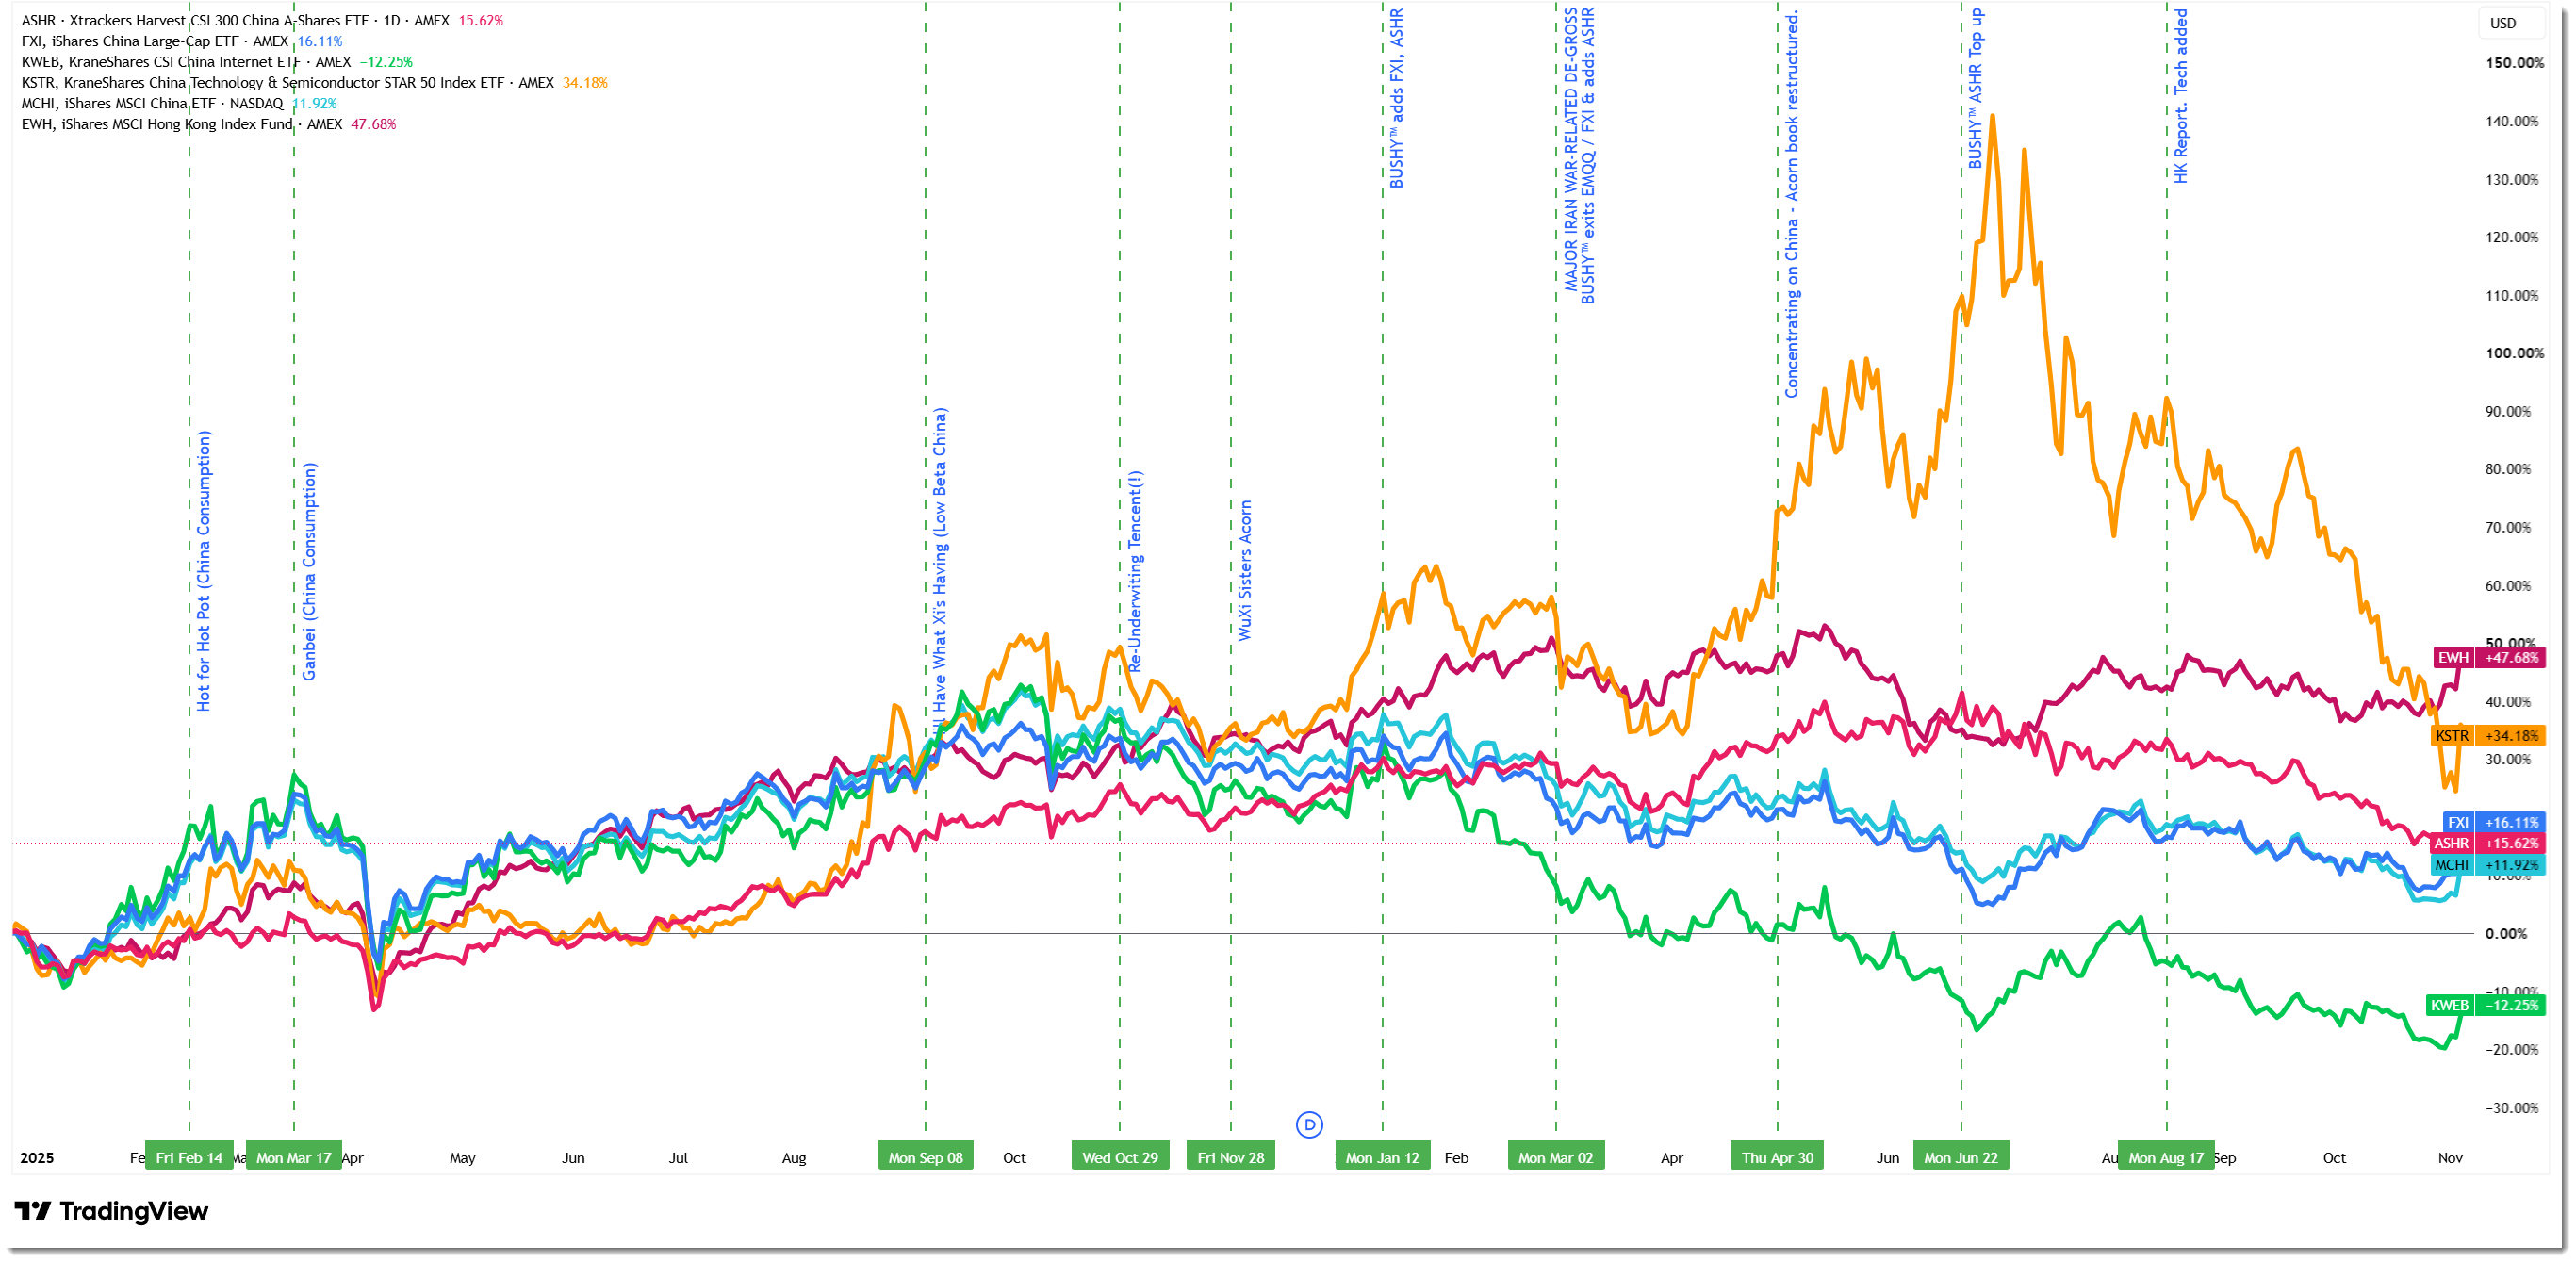
Away from the beta, the 🐿️’s approach to picking stocks in China has been to try and spend less time thinking about what Beijing should do economically and more time listening to what they intend to do. This gave rise to a portfolio pivot away from the consumption recovery story towards lower beta stocks in September of last year (‘I’ll have what Xi’s having’).
In May, my (much reduced) China allocation had too much exposure to the consumer recovery theme and too little to the industrial and technological resilience theme (but about which Beijing was being so vocal). I went through the process of structuring a new concentrated China basket:

The plan was to sell/trim the stocks leaving the portfolio and fill out the new names for the basket as and when we saw normalized risk conditions. We are obviously still waiting for that moment…
But took action anyway…
