

This week the 🐿️ answers the (perfectly reasonable!) question as to why almost 8% of his beta portfolio (BUSHY™) is sitting in emerging market local currency fixed income paper (with over half of that exposure in Africa!). September was a tough month for carry traders. It’s time to re-underwrite.
The Global Bond Headache
2 decade highs in US Treasury yields and stress in the French OATs market have made all of the recent headlines and the US dollar index looks to be finally following through on that long-threatened breakout. BUSHY™’s EURUSD puts well and truly earned their keep in the past week...
With this backdrop, less column inches have been dedicated to the pain in emerging market bonds. As such, you need to keep an eye on the experts. The ‘Hunger Games’ appear to have come for EM borrowers.

TEI 0.00%↑, the Templeton Emerging Markets Income Fund - an unconstrained closed-end fund invested in local currency EM paper - has been a bedrock of my BUSHY™ beta portfolio since 2023.
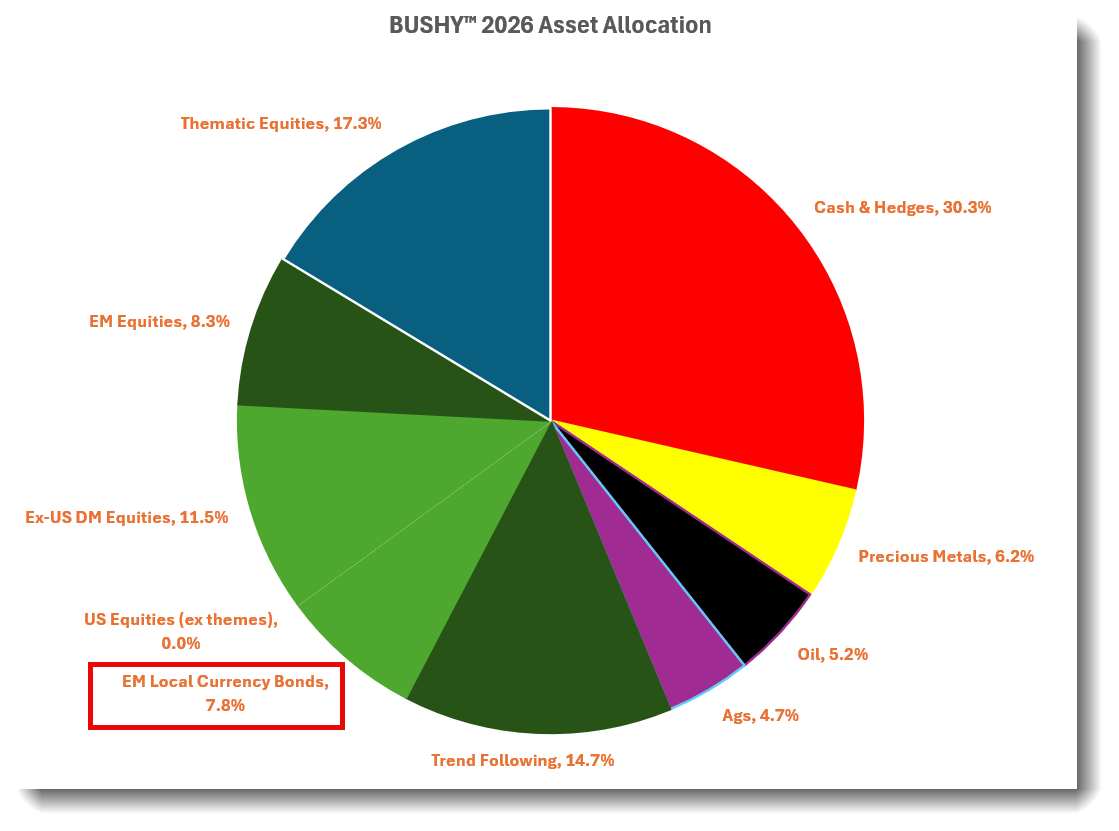
What is BUSHY™? It is Blind Squirrel Macro’s flagship beta portfolio, designed to be the antidote to the classic '60/40' retirement portfolio.
BUSHY™ invests globally across all major asset classes (equities, fixed income and commodities), primarily via US listed ETFs and closed-end funds. Current asset allocation set out in the chart below.
It is primarily long-only and will occasionally manage tail risks with simple listed option strategies. The investment strategy targets long-term capital appreciation with a low volatility and drawdown risk profile.
A quick reminder that the BUSHY™ portfolio is investable via a single click on the Plutus platform - full details in my July launch note linked below.

With a near double-digit (non-manufactured) dividend yield (I always re-invest the monthly payout) TEI has been a steady performer throughout that period. I even added to the position in mid June. Then came September…
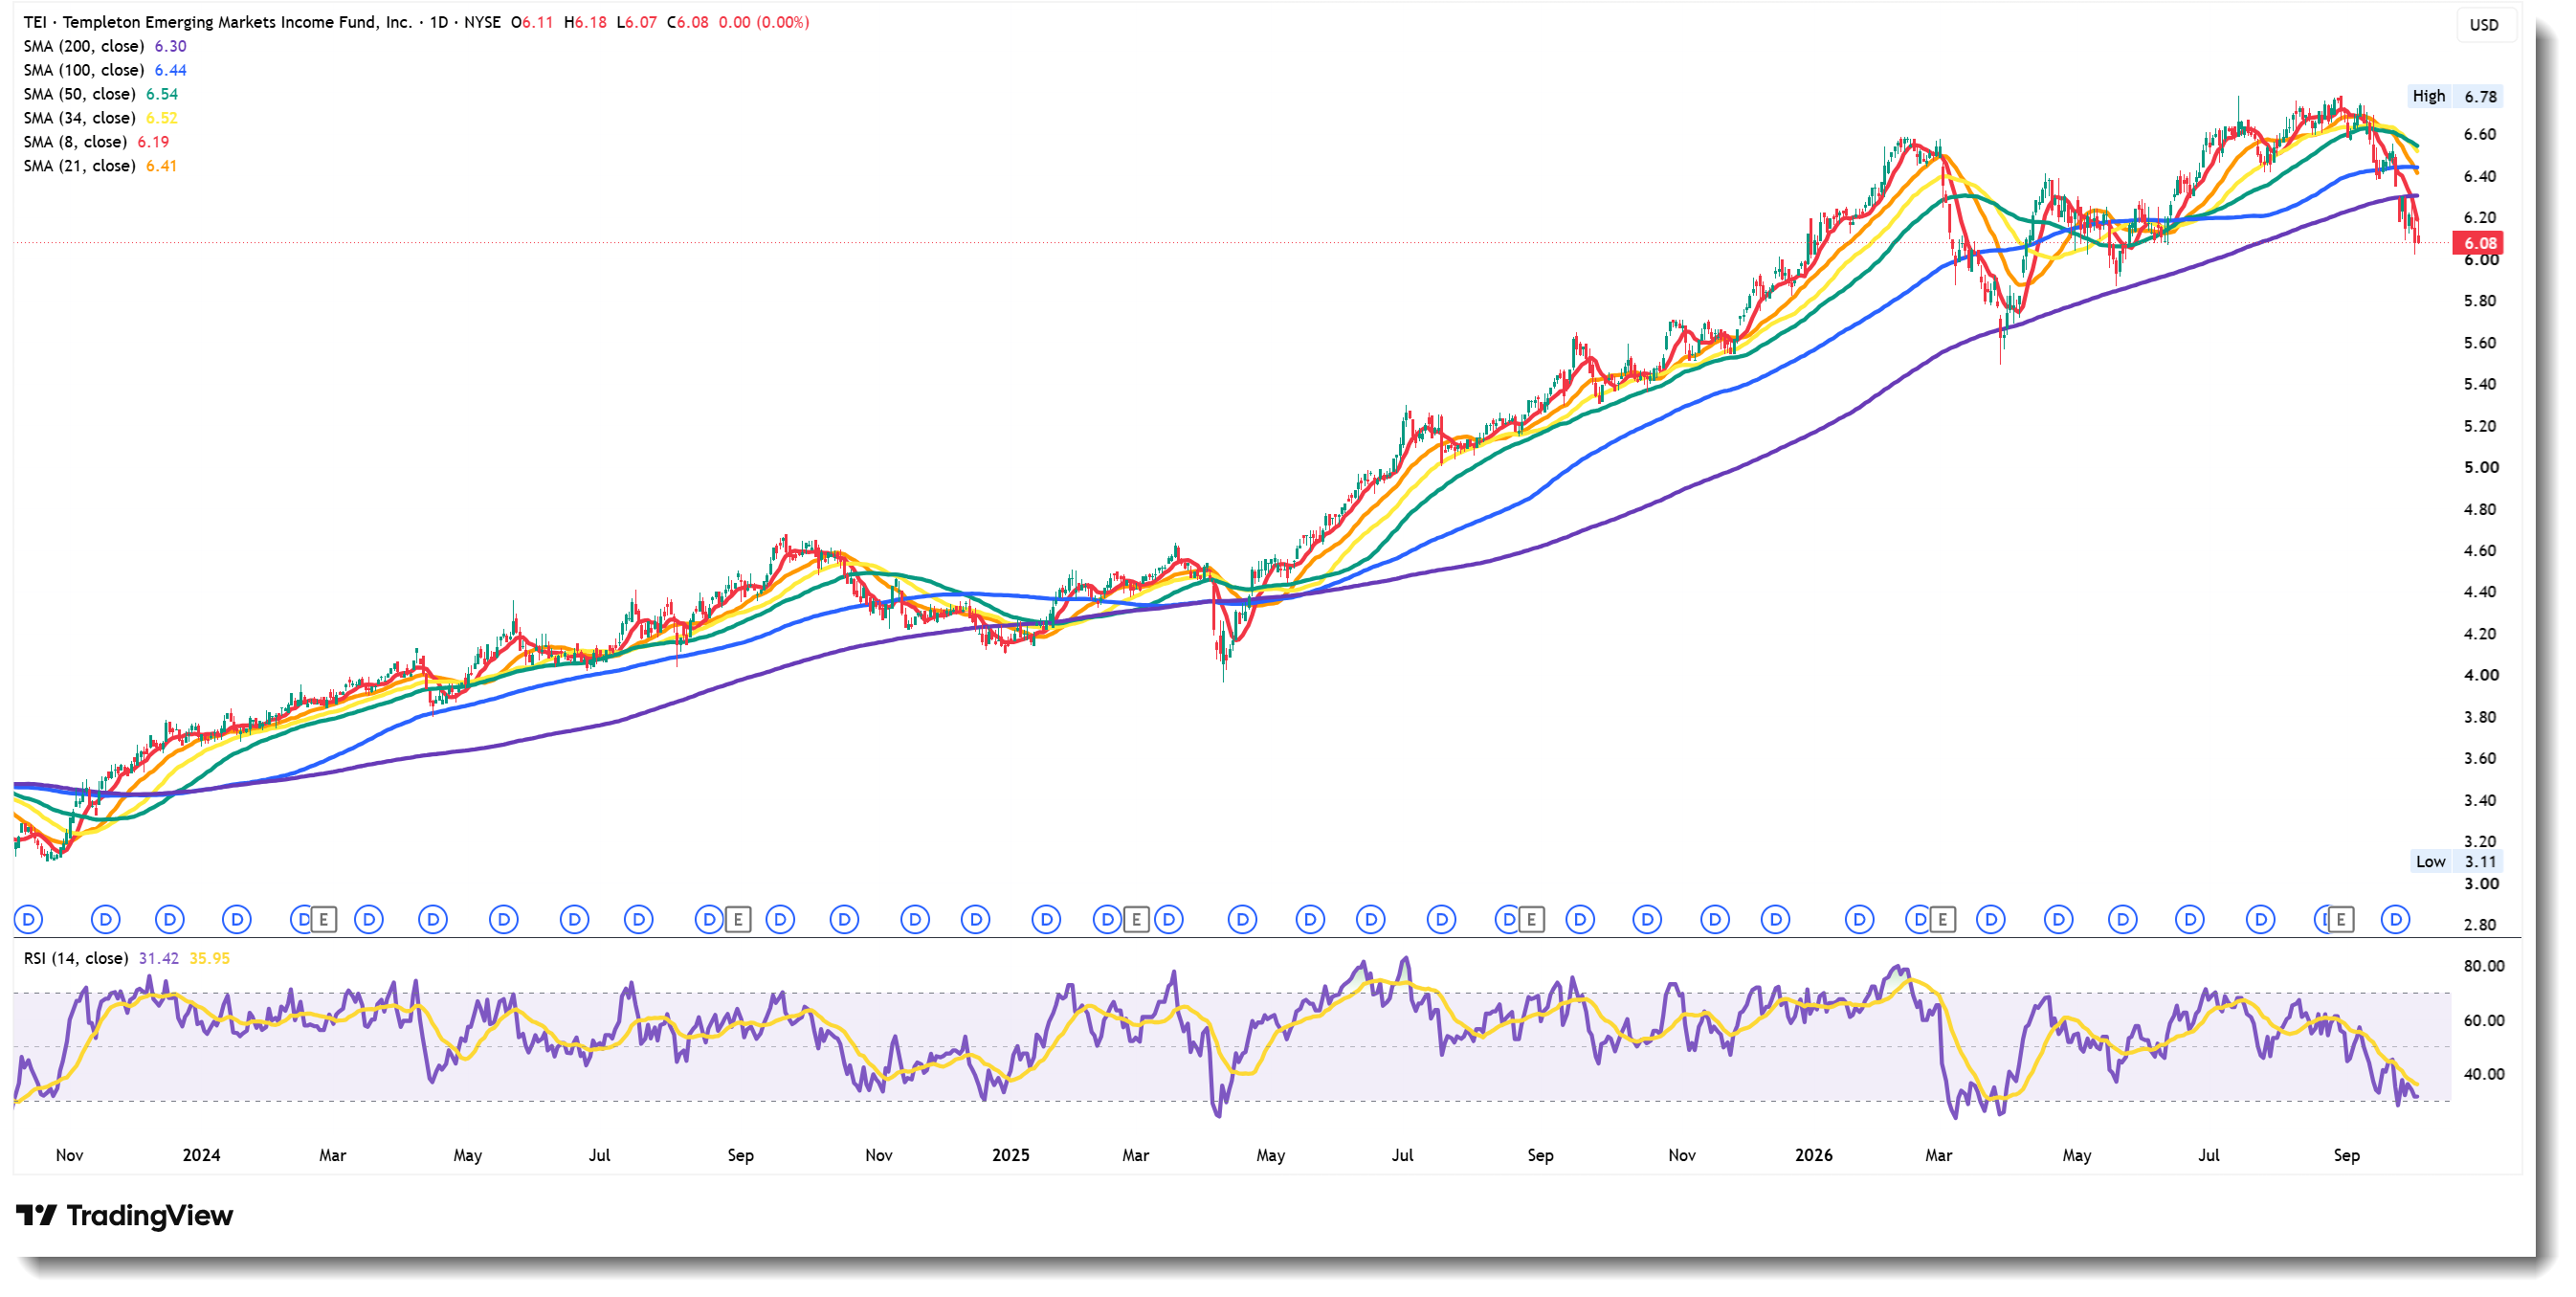
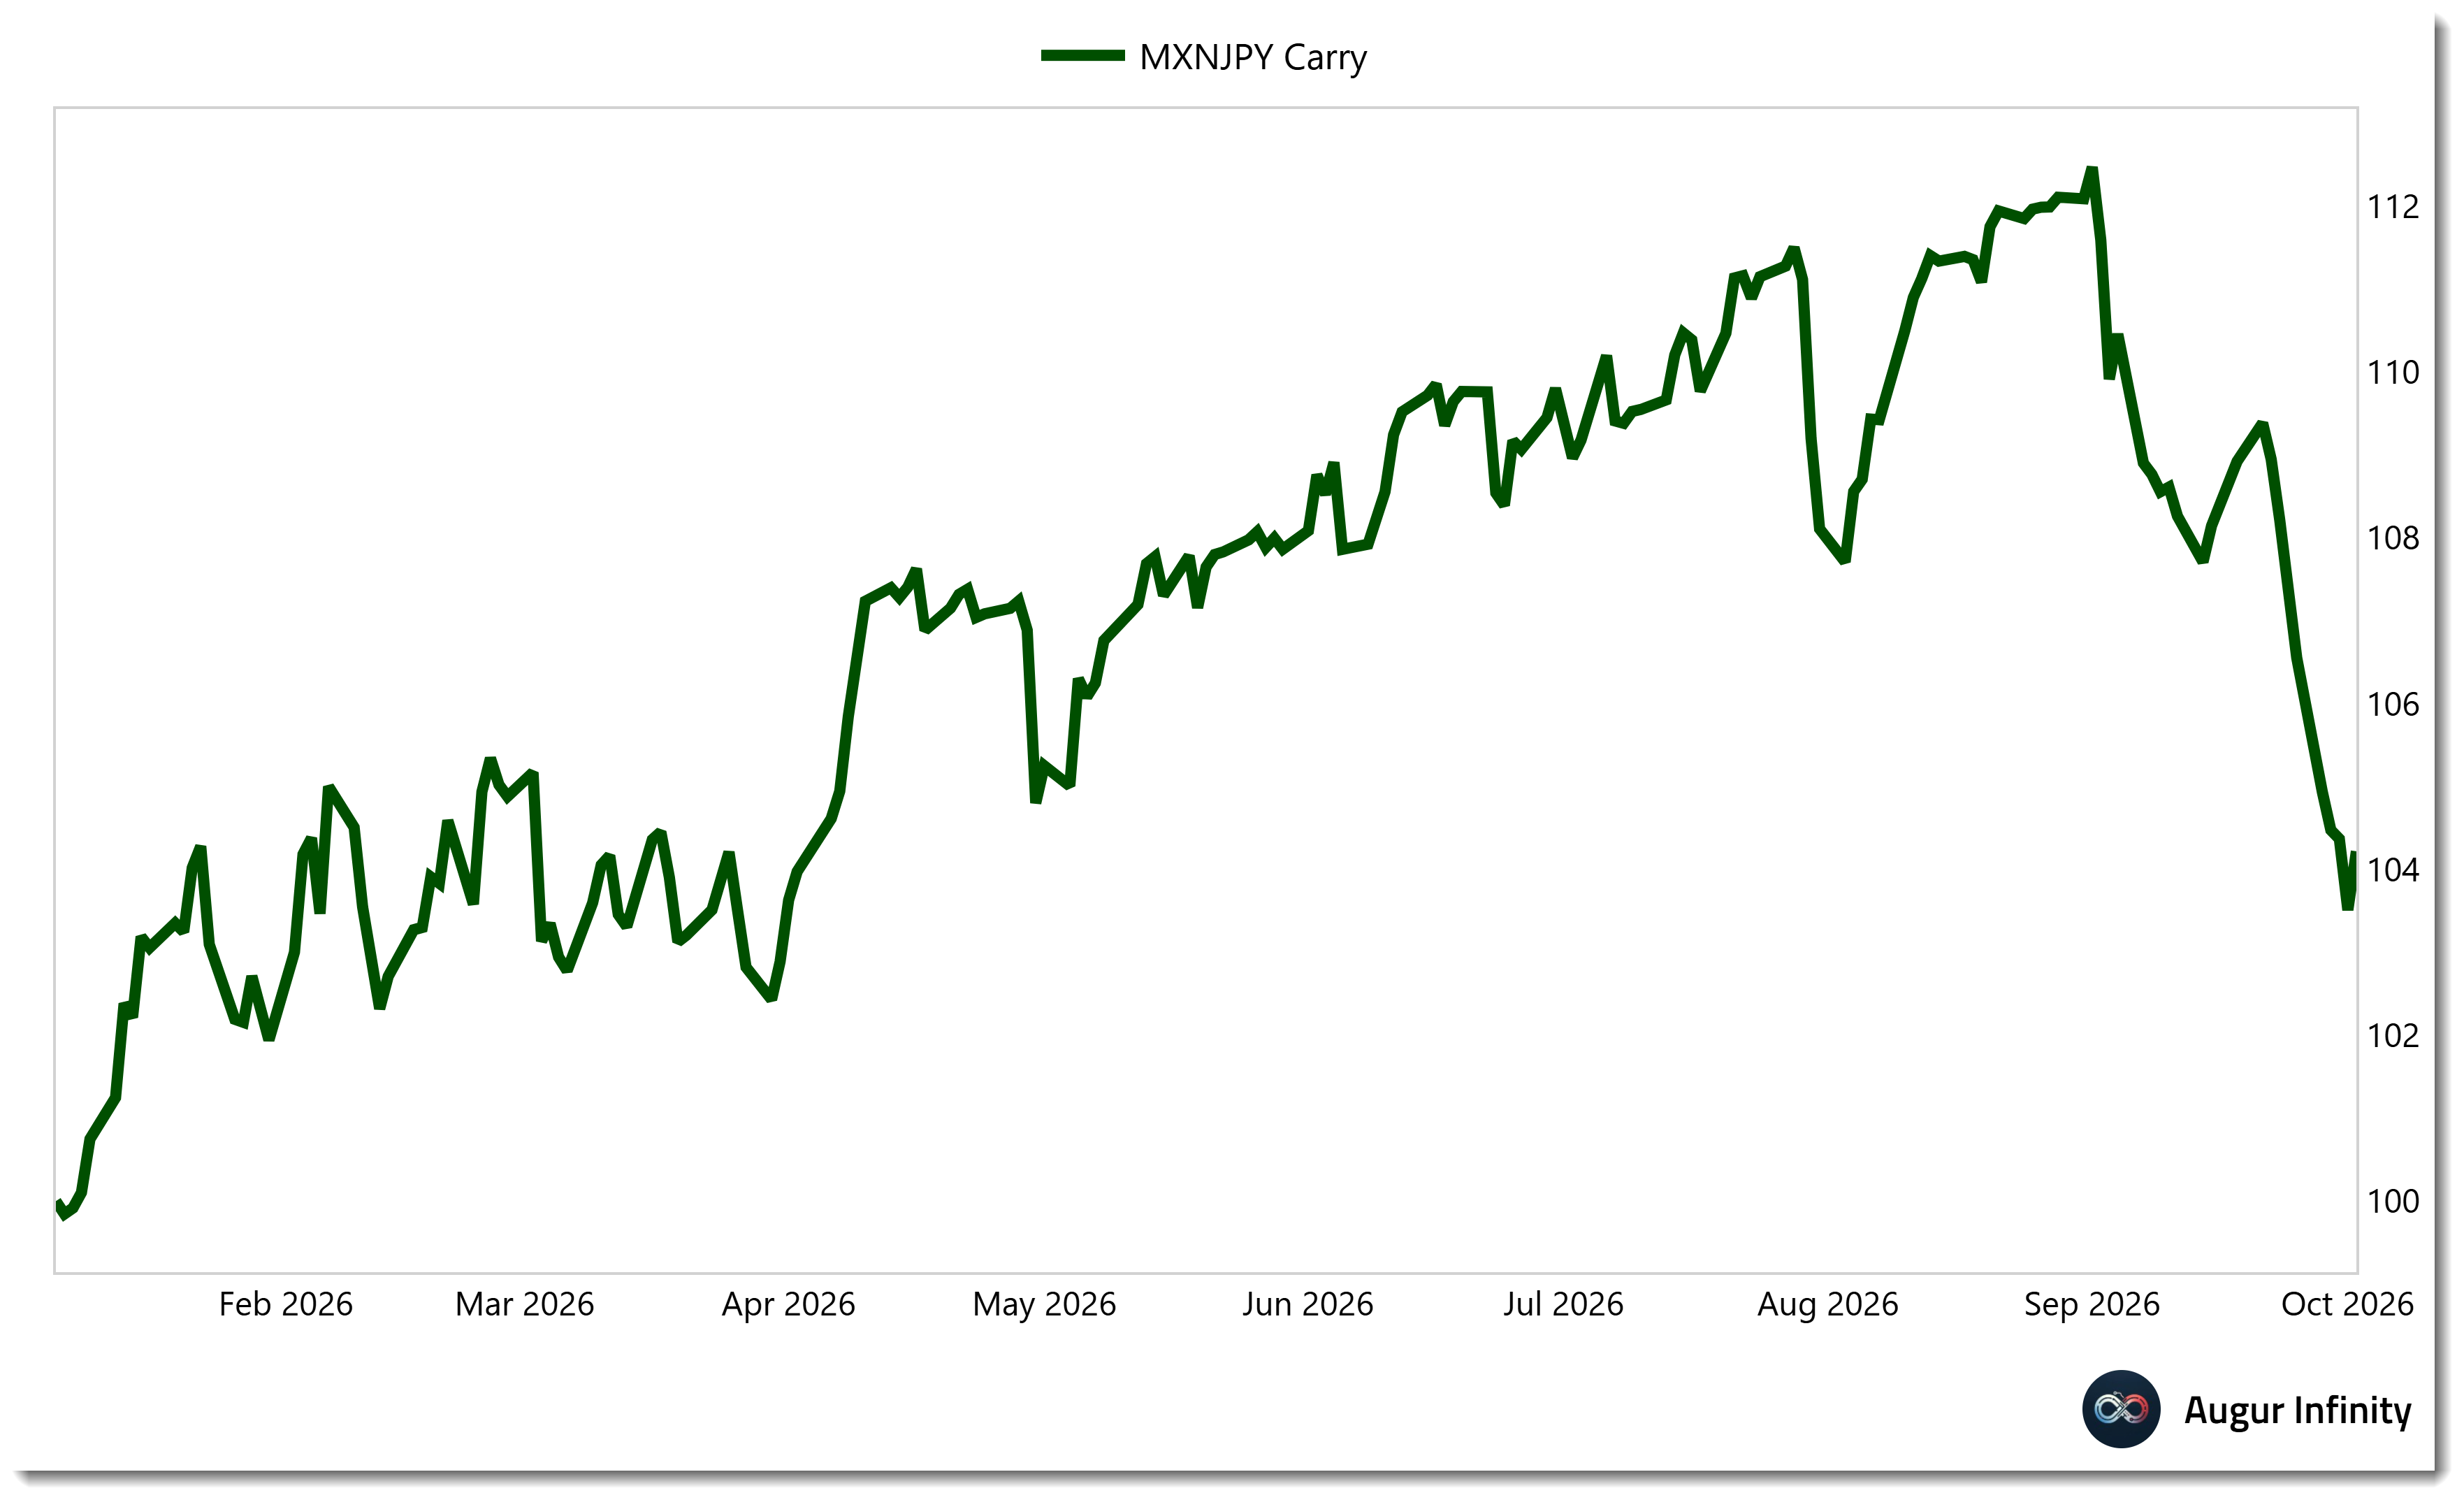
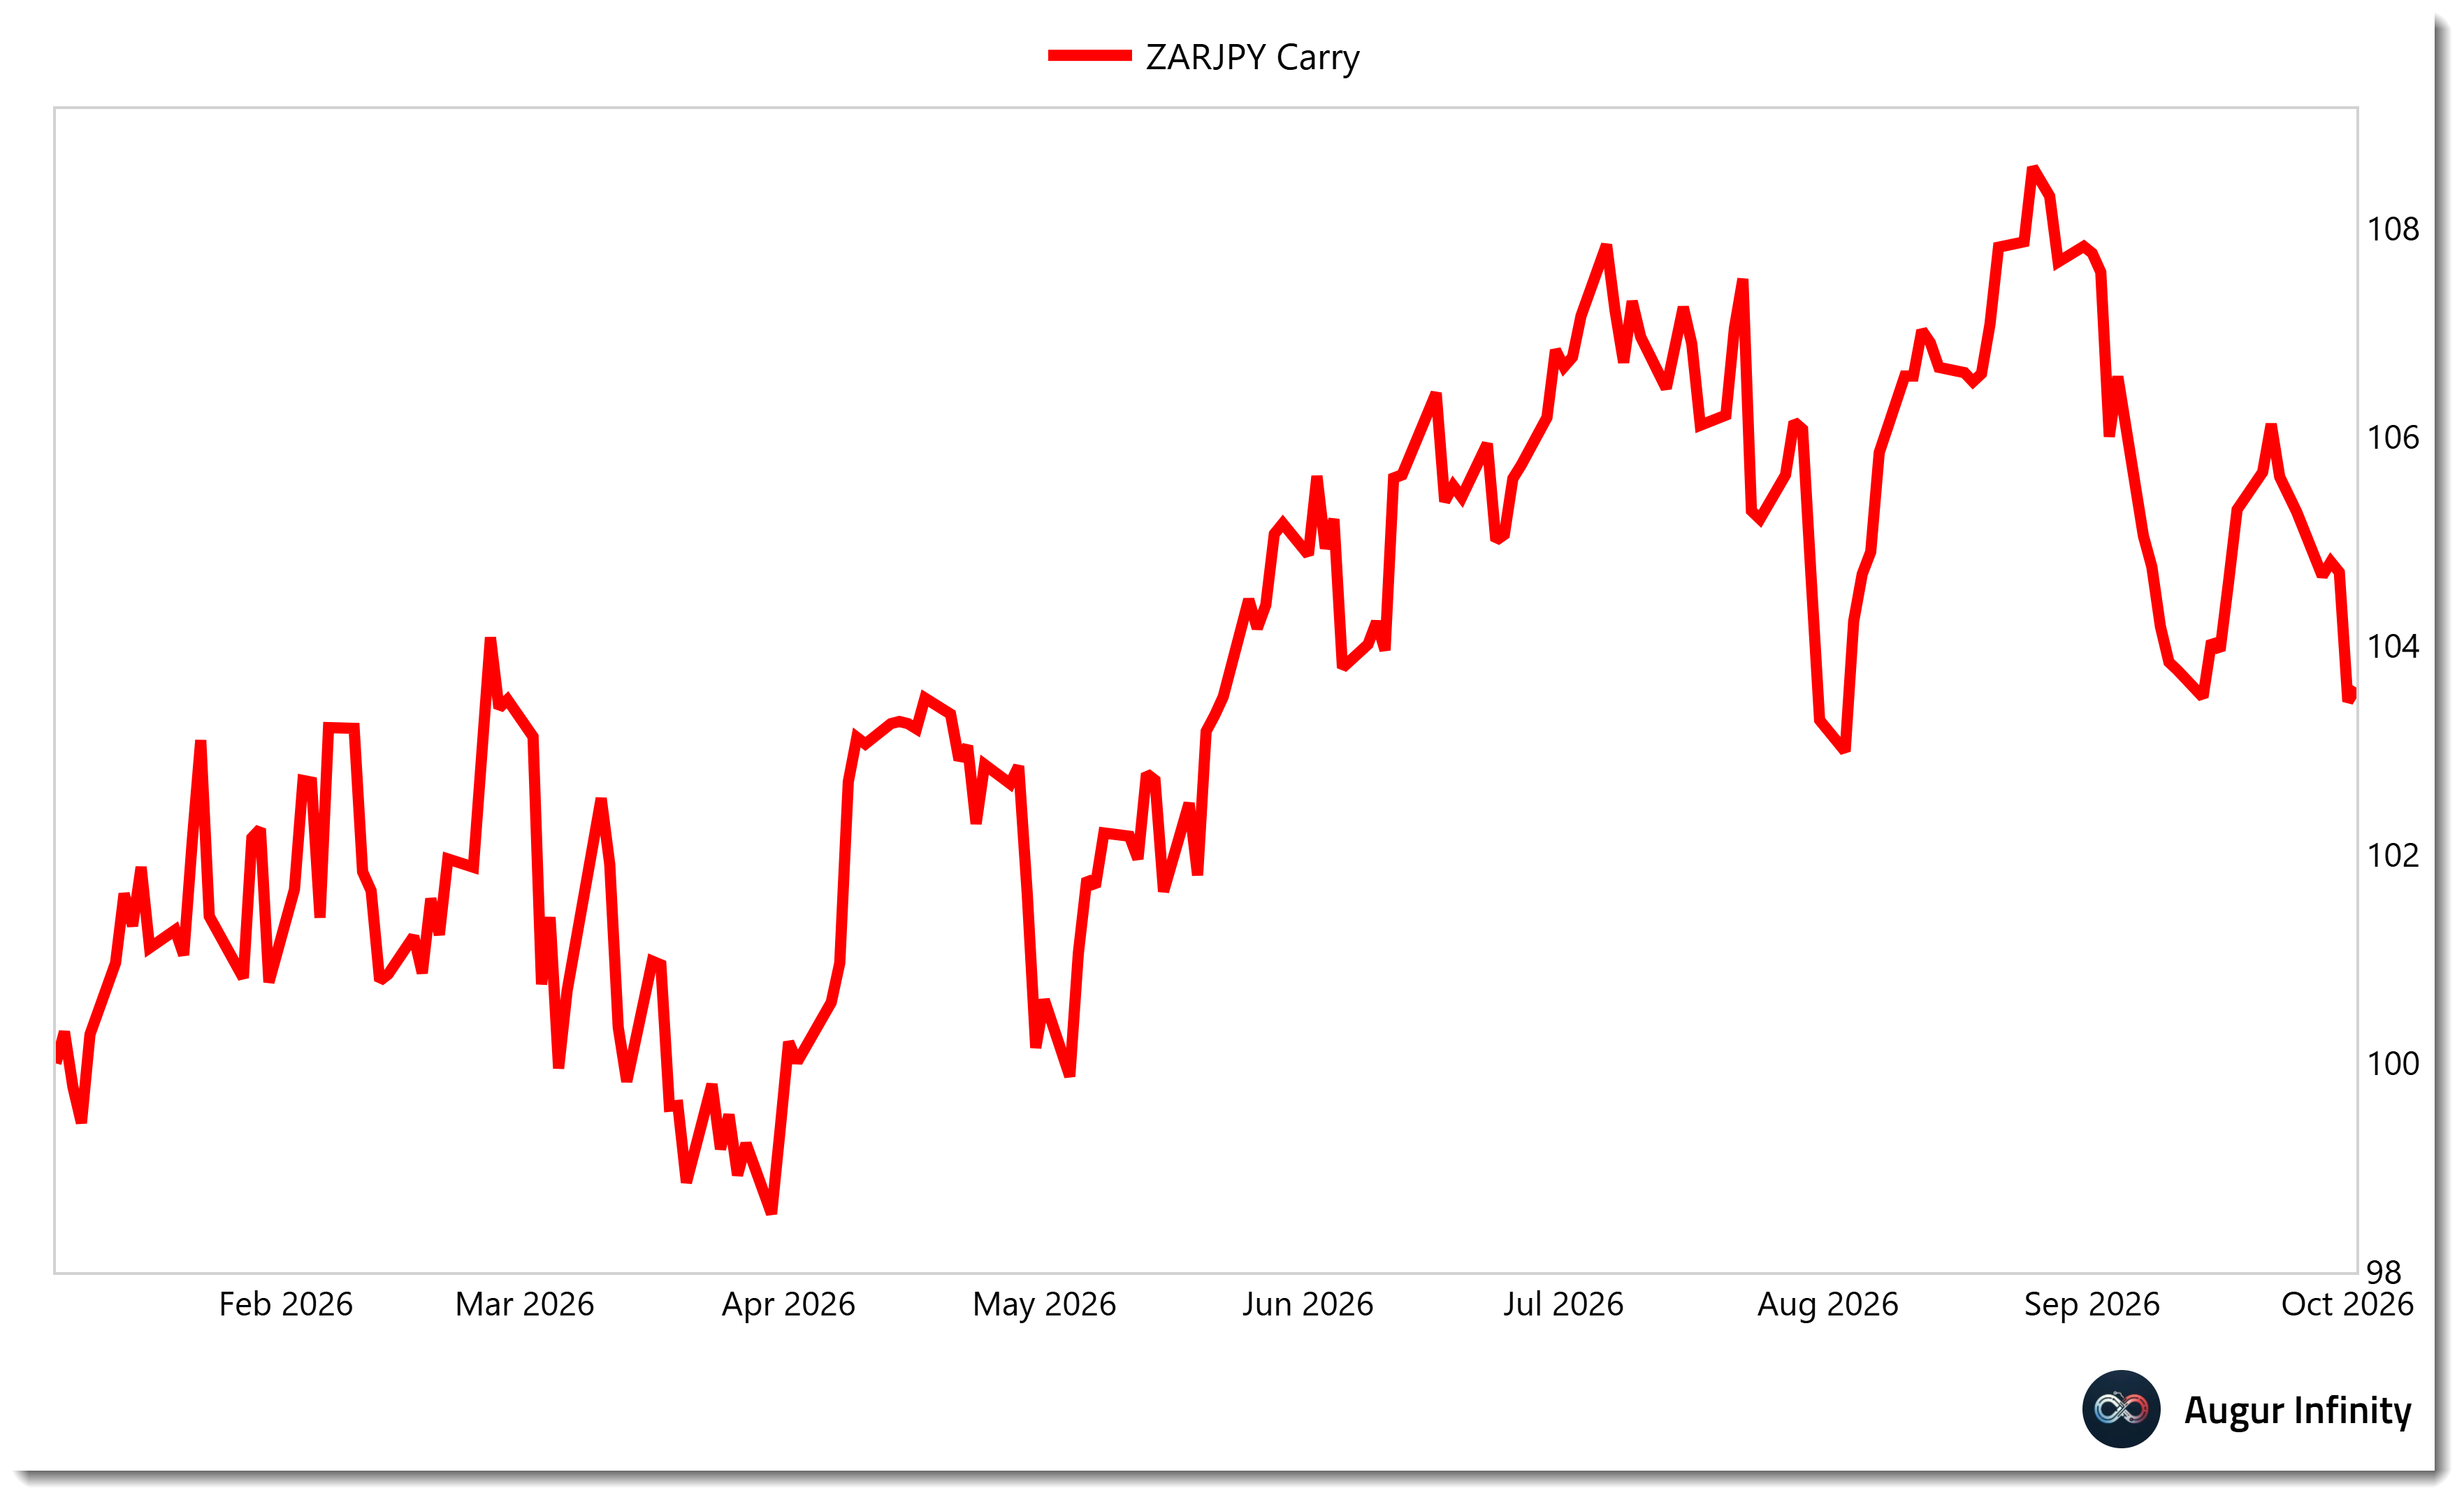
Bond bulls and carry traders got smashed last month. MXN and ZAR - the two currencies doing much of the recent performance heavy lifting inside TEI’s book - gave back, between them, most of their year.
The 2 charts below illustrate the impact on JPY-funded Mexican Peso…
… and South African Rand carry traders:
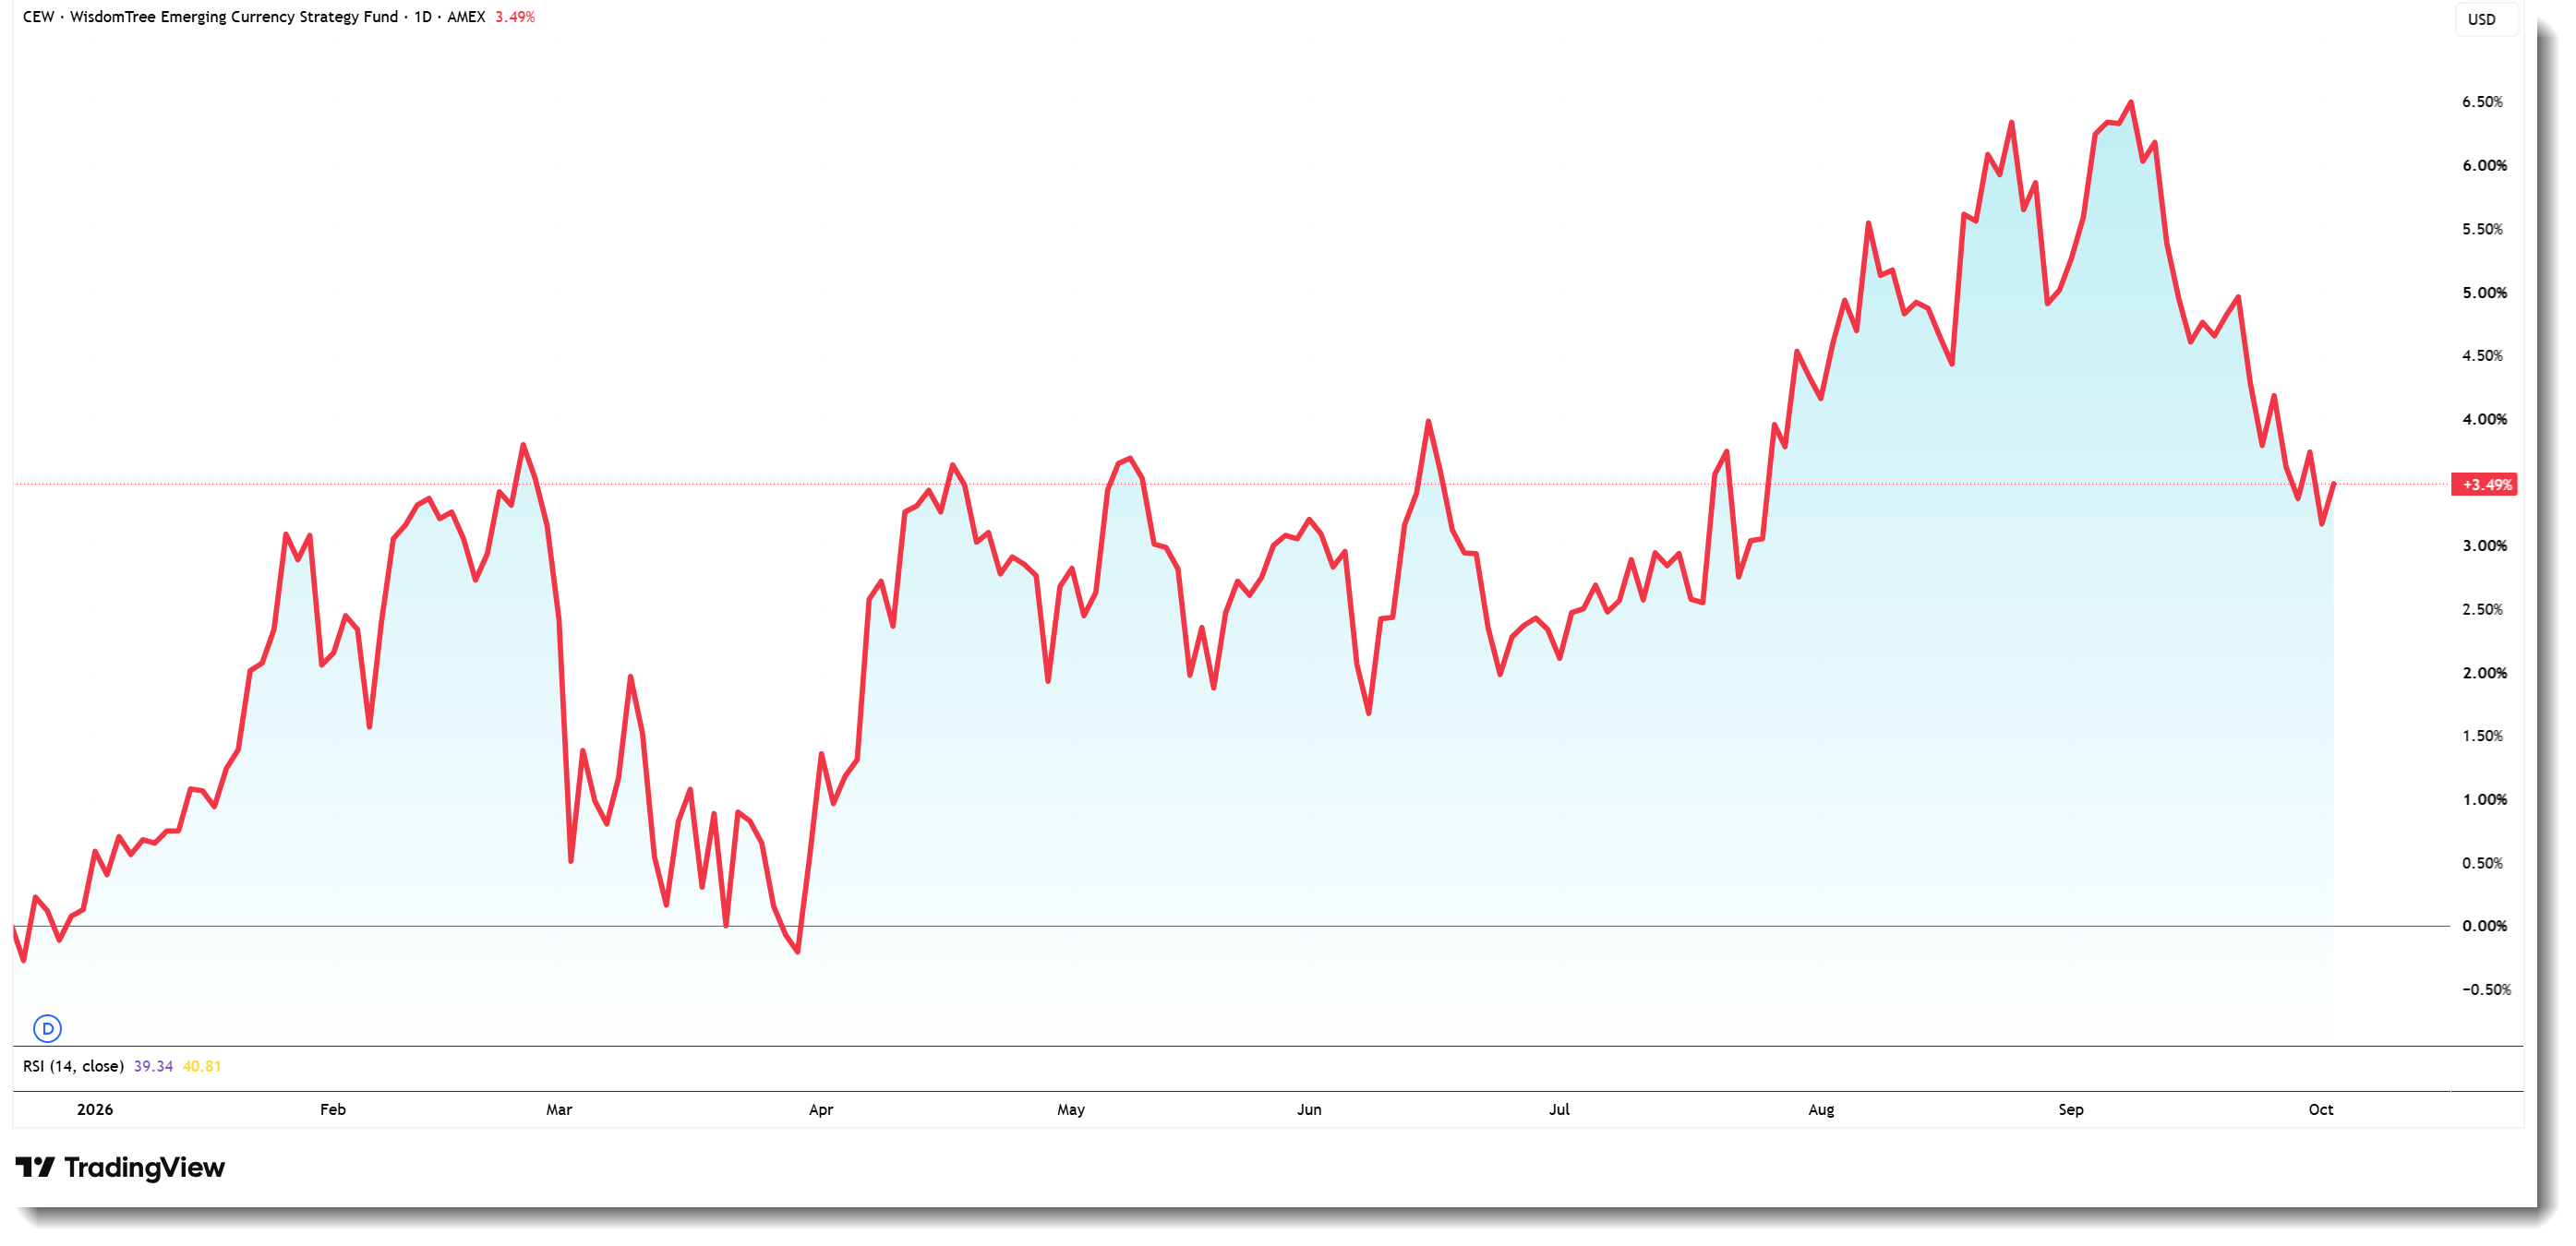
$CEW - The WisdomTree EM Currency ETF gave back 50% of its year in September:
TEI’s NAV total return was running at +11% at the end of August. The closed end fund just lost 9% in price (not NAV - more on that later) over the course of September.
EM local currency paper has bounced back well from carry shocks of the past (summer of 2023, ‘Liberation Week’ and the outset of the Iran War). Will it do so again?
